Global Energy Market Overview: Oil, Gas, Power, Coal, and Renewables as of September 10, 2026
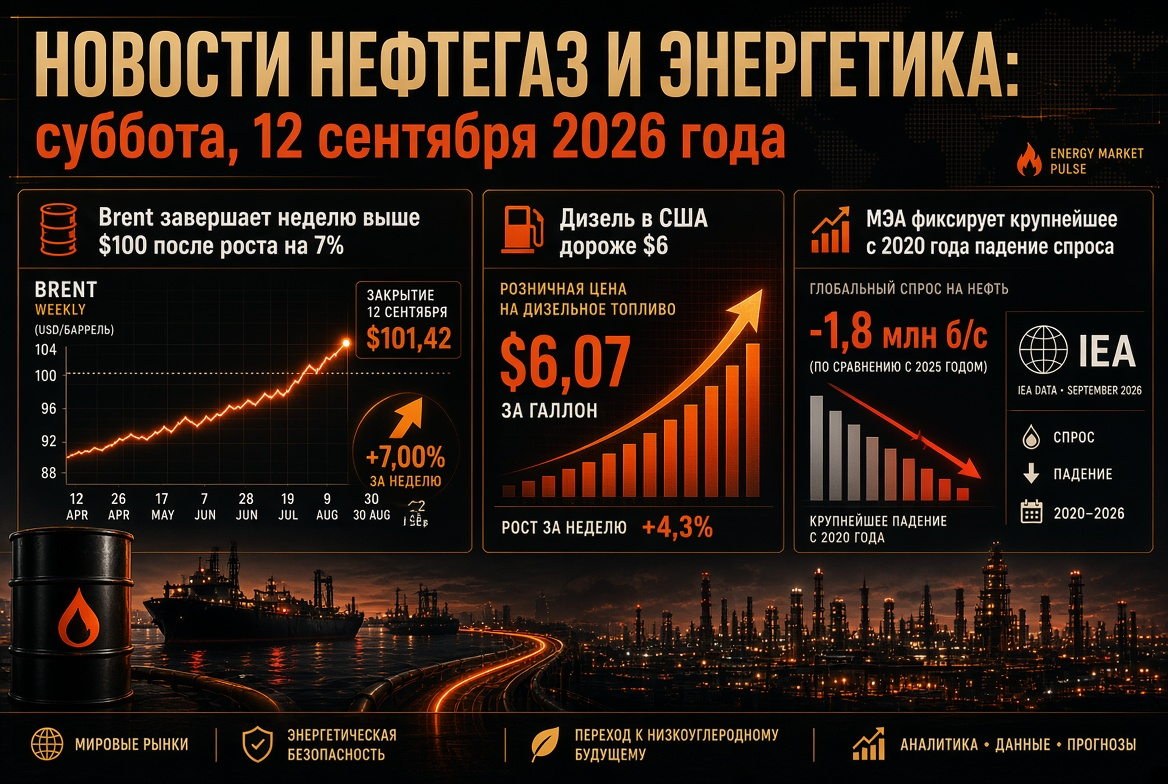
Top Story: Brent Above $100 — Strikes on Tankers and Tehran's Response
Oil prices are rising for the fourth consecutive session, with direct military escalation in the Persian Gulf being the trigger for this new uptick. The U.S. Central Command reported the destruction of five Iranian oil tankers in the Gulf of Oman and near Kharg island in response to attempts to attack American ships; a total of ten vessels from the "shadow fleet" were disabled within a week, according to the Pentagon. Iran claimed to have struck the Muwaffaq Salti base in Jordan (18 missiles intercepted), attacked two U.S. Navy destroyers, and targeted ten ships near the Strait of Hormuz. The UK Maritime Trade Operations (UKMTO) reported an unknown projectile hitting a tanker near Iraq's Al-Faw and damaging a vessel at Port Rashid in the UAE.
A key threat to shipping is the "no-go zone" declared by Tehran outside the strait, where Iranian forces intend to stop vessels without permission. For traders and insurers, this means further increases in military premiums and a reduction in the number of shipowners willing to operate in the region. In response, Washington has expanded its sanctions campaign against Iranian aviation, while Seoul is considering participating in securing the strait.
Oil Market: Prices, Dynamics, and Forecasts
Key indicators of the oil market as of Thursday morning:
- Brent (November, ICE): Wednesday peak at $100.19 per barrel, first time above $100 since July 24; followed by consolidation near $99.7–100.5.
- WTI (October, NYMEX): Around $94.7, approximately 2% increase for the session.
- Dynamics: Since August 31, Brent has gained about 13.5%, and nearly 40% since the start of the war with Iran in late February; the April peak of the year exceeded $125.
- Forecasts: Goldman Sachs allows for $120 if attacks on vessels in the Hormuz and Red seas escalate, with a return to $80 if exports normalize; ING expects a substantial risk premium to remain until negotiations resume.
The fundamental backdrop remains tight. According to EIA estimates, global oil inventories decreased by 4.2 million barrels per day in Q2 and by another 3.8 million barrels per day in Q3; transit through Hormuz in Q2 amounted to only 4.9 million barrels per day compared to 21.6 million before the conflict. The August agency forecast — $85 per barrel in Q3 and $78 in Q4 — appears outdated against current quotes, and the September STEO release published on September 9 will be closely scrutinized by the market in light of the "hundreds" scenario. The U.S. strategic reserve stands at around 286.6 million barrels, limiting Washington's ability to counter price shocks with interventions.
Middle East: Dual Saudi Arabia Blockade
The second front of risk is the Red Sea. On September 8, the Houthis struck facilities in Abha, Khamis Mushait, Jizan, and Najran: 73 people were injured, and fires broke out at the Aramco refinery in Jizan with a capacity of 400,000 barrels per day. Simultaneously, the movement has launched a campaign for control over Bab-el-Mandeb. The issue for oil supply is that with Hormuz closed, the Red Sea has become the kingdom's main artery: the East-to-West pipeline is operating at a record 7 million barrels per day, and the Yanbu terminal accounts for over 90% of Saudi oil's maritime exports. The defense pact between Riyadh, Turkey, and Pakistan has not eliminated threats to infrastructure. Any disruption at Yanbu would mean the largest exporter would exit the market for the duration of closure of both straits.
Gas Market: TTF Above $950, Storage at Lowest Since 2011
The European gas market is moving counter to seasonal logic. October futures on TTF reached 78.8 euros/MWh on September 9 (about $970 per thousand cubic meters), up nearly 4% for the day; since the beginning of the year, prices have increased by approximately 120%. Key parameters:
- EU gas storage levels — 66.9% as of September 7, around 71.7 billion cubic meters; a record low for this date since observations began in 2011 and down 13.8 billion cubic meters from last year's level.
- Germany — approximately 53%, the worst performance among major economies; Italy is the only large market close to comfortable levels of 80%+.
- Target ratio — 90% in the window between October 1 and December 1, with a deviation of 10 percentage points; only about 62% of the required volumes have been injected since April.
The European Commission, following the Gas Coordination Group meeting on September 3, stated that there is no immediate threat to supply security and sees no grounds for intervention, citing diversification, regasification capacities, and reduced demand. At the same time, LNG production in Qatar remains halted, and Europe is forced to compete with Asia for tankers at peak prices. For the EU industry, this means entering the heating season with the highest injection costs in four years.
LNG and Coal: Gas Deficit Supports Coal Generation
The LNG deficit in 2026 is estimated at around 35 million tonnes, forcing import-dependent countries in Northeast Asia to increase coal generation: in South Korea, it has risen by nearly 40%, and in Japan by more than 11%. Global demand for coal may increase by about 3%, approaching 9.1 billion tonnes. For coal exporters — Indonesia, Australia, Russia, and South Africa — this creates an unanticipated window of demand against the long-term decarbonization trend.
China and Asia: Oil Imports Recovering from Decade Low
China's customs statistics for August revealed a second consecutive month of growth: oil imports amounted to 37.93 million tonnes (8.93 million barrels per day), +6.2% compared to July, but still 23.4% lower than last year's level; over eight months, purchases have decreased by 14.6%. Chinese refineries are actively increasing purchases of Russian ESPO oil bypassing Hormuz and are exploring atypical markets, including Argentina. The export of oil products surged by 29% to 6 million tonnes amid a global diesel shortage, while domestic demand for gasoline and diesel remains 8-9% lower than last year. The reduction in inventories slowed to 550,000 barrels per day, indicating a gradual return of Beijing to the spot market.
Russia: Urals Discount, Exports, and Second Wave of Fuel Crisis
The high Brent price partially compensates Russian companies for the expanded discount: after the expiration of the American license for transactions with Russian oil, the discount on Urals reached $23-24 per barrel in the summer, with the average annual level estimated at $17-22. The domestic market for oil products remains in crisis mode:
- Exchange sales of gasoline from September 1-4 increased by 69% compared to August, reaching 72.75 thousand tonnes, but by September 7, they fell to 12.24 thousand tonnes due to unscheduled refinery repairs;
- Unsatisfied solvent demand — 37.7 thousand tonnes for AI-92 and 35.3 thousand tonnes for AI-95; since May, only about 41% of exchange contracts have been fulfilled;
- Since the beginning of the year, 5.44 million tonnes of gasoline have been sold on the exchange — 23.7% less than last year;
- The ban on gasoline exports has been extended until January 31, 2027; the Ministry of Energy is discussing restrictions on diesel exports during the repair period and winter demand, and import supplies from India have begun.
Power and Renewables: Structural Trend Unfolding
Amid the raw material shock, the energy transition is accelerating. According to Ember, in 2025, renewable sources surpassed coal for the first time in a century in global generation (33.8% vs. 33.0%), and in May 2026, solar power overtook coal in the energy balance of the U.S. for the first time (12.8% vs. 12.2%). Africa is headed for a record year with a 45% increase in solar capacity installations. Global electricity demand in 2026 is expected to grow by 3.6% due to electric transport, air conditioning, and data centers for AI. For investors in renewables, storage, and network infrastructures, expensive gas acts as an additional argument rather than a deterrent.
Thursday Calendar: OPEC, EIA, and U.S. Inflation
September 10 is one of the busiest days of the month for participants in the energy market. OPEC will release its monthly review with updated estimates of demand and production, which will indicate how much the cartel accounts for the decline in consumption in Asia. Due to the holiday schedule, the EIA is releasing weekly statistics on oil and petroleum product inventories on Thursday — after a series of reductions in U.S. commercial inventories below the five-year minimum, this data is critical for WTI. In the U.S., the Producer Price Index for August will be released, followed by the IEA review and consumer inflation on Friday, which will affect the rhetoric of the Federal Reserve. The next OPEC+ meeting is scheduled for October 4; October quotas remain unchanged.
Conclusions and Risks for Investors and Energy Companies
- Oil. The stability of Brent above $100 depends on whether the attacks on tankers escalate into a full closure of Hormuz and Bab-el-Mandeb; the range of scenarios for the quarter is between $80 and $120.
- Gas. Europe is entering winter with an historic shortage of reserves; a cold November or another LNG supply disruption could return TTF to four-digit levels.
- Coal and Refineries. The gas and diesel deficits support the coal generation and refining margins, but concentrate profits in regions outside the conflict zone.
- Russia. High oil prices soften budgetary risks, but the domestic fuel market remains vulnerable until the completion of refinery repairs.
- Renewables. Renewable energy remains the only predictable element of the global energy balance and the main benchmark for long-term investments.
The day's outcome for the global energy sector: the short-term price of oil and gas is dictated by the military dynamics of the Persian Gulf and Red Sea, the medium-term by Europe and Asia's ability to weather the winter with semi-empty storages, and the long-term by the pace of the energy transition. In this context, scenario planning, logistics diversification, and hedging discipline are becoming essential for energy market participants’ survival, rather than optional.