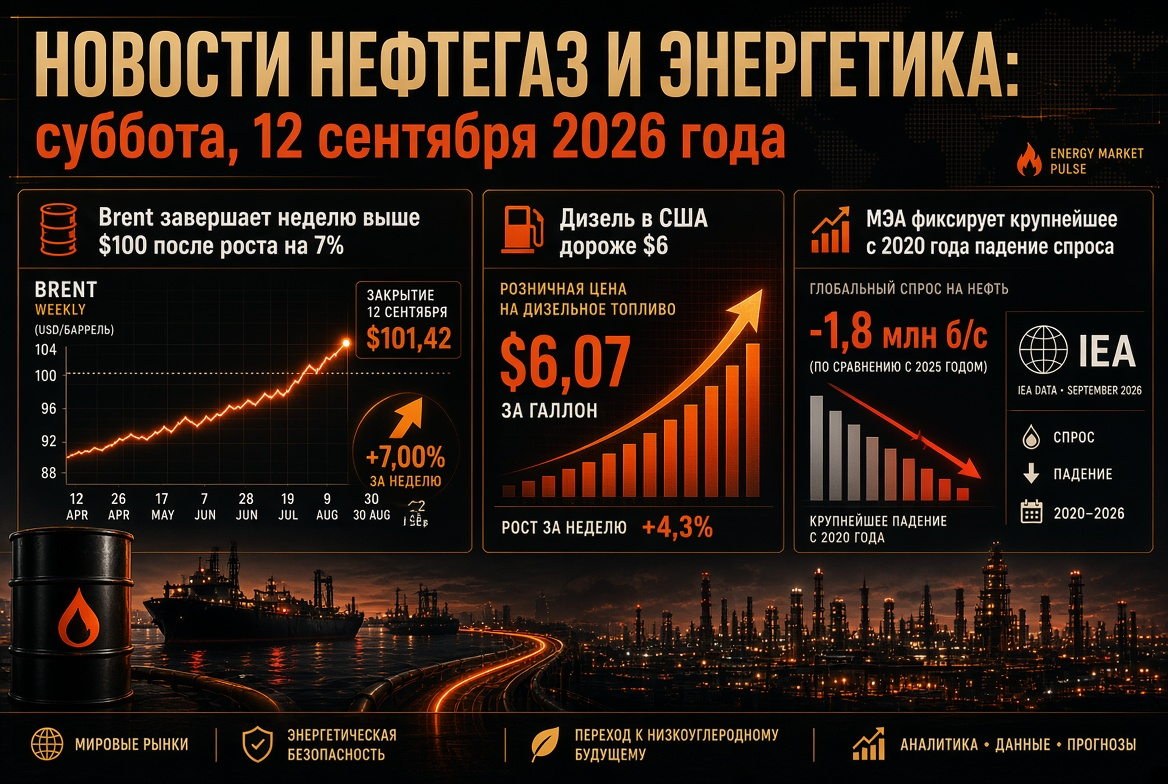
Oil and Gas News and Energy: Friday, September 11, 2026 — Brent Stabilizes Above $102 Following Largest Tanker Attack in the Strait of Hormuz, Gas in Europe Exceeds €80
The global fuel and energy complex enters Friday, September 11, 2026, in a state of complete price shock. Oil prices for Brent have surpassed $102 per barrel for the first time since late May, while Europe's gas benchmark TTF has breached the €80 mark for the first time since January 2023; underground gas storage in the EU is only two-thirds full compared to a seasonal norm of over 80%. The trigger has been the most extensive wave of maritime attacks since the war began on shipping in the Strait of Hormuz, compounded by a second front in the Red Sea. For investors, oil and fuel companies, refinery operators, and participants in the markets for gas, coal, electricity, and renewables, the crucial question of the day is: how much more geopolitical premium can the global economy absorb before demand for energy resources begins to collapse.
Main Topic of the Day: Tanker War in the Strait of Hormuz Escalates
On the night of Wednesday, the United States sank five Iranian oil tankers in the Gulf of Oman and near the island of Kharg as part of a "tanker-for-tanker" policy announced by Washington in early September. Tehran responded with attacks on ten vessels near the Strait of Hormuz and a missile strike on the U.S. base in Al-Azraq, Jordan. According to maritime monitors, at least one crew member from a tanker has been confirmed dead, and another is reported missing. This series represents the largest assault on commercial shipping since the war began on February 28.
The physical landscape for the oil and gas market is deteriorating in three dimensions:
- Expansion of the Restricted Zone. The IRGC has declared a maritime restricted zone from Chabahar through the Gulf of Oman to the Arabian Sea, urging tanker crews off the coasts of Bahrain and Kuwait to leave their vessels immediately.
- Insurance and Freight. New incidents effectively nullify the availability of war-risk insurance for vessels taking "unauthorized" routes, cementing transit through the strait at minimal levels.
- Environmental Risk. Damaged and partially submerged tankers in the Persian Gulf pose a threat to desalination stations and coastal infrastructure in Gulf countries.
Oil: Brent Above $102, WTI at $96 — Market Adjusting Price Expectations
Key oil market benchmarks for Friday morning:
- Brent (November contract, ICE): rose 3.4% to $101.21 on Wednesday, briefly reaching $102.4–102.9 on Thursday — the highest since May 22. The annual peak of $126.41 (April 30) remains a target for the bearish scenario regarding Hormuz.
- WTI (October contract, NYMEX): stabilized in the $96–97 per barrel range.
- Forecasts: The September review from the U.S. Department of Energy projected an average price for Brent at around $90 for the second half of 2026, decreasing to $74 in 2027 — figures that already appear outdated just two days after publication at current quotes. Long-term models from several Asian banks indicate prices of $113–114 within 12 months.
Stock Levels and Physical Balance
Global oil stocks, according to U.S. regulators, have decreased by approximately 400 million barrels since the beginning of the year, and the recovery of production in the Middle East to pre-war levels has been postponed to the second quarter of 2027. The U.S. strategic reserve is approximately 286.6 million barrels, the lowest since the early 1980s. Commercial oil inventories in the U.S. before the postponed weekly report scheduled for Thursday stood at 424.5 million barrels with a refinery utilization rate of 98%; distillate inventories are 14% below the five-year average and are projected to fall below 100 million barrels by September.
OPEC+ and Monthly Reports
Seven OPEC+ countries at the meeting on September 6 kept the October quotas unchanged after six consecutive months of production increases; the next meeting is scheduled for October 4. The monthly report from OPEC, due on Thursday, will provide a framework for demand following an August revision of the consumption growth forecast for 2026 to 0.58 million barrels per day. The International Energy Agency is anticipating a decrease in global demand by 1.6 million barrels per day alongside an 1.8 million barrels per day deficit in the third quarter and 8.3 million barrels per day in Gulf production, which is still halted.
Red Sea: Houthi Strikes on Jazan Refinery Open Second Front for Oil Exports
While the market has been focused on Hormuz, Yemeni Houthis conducted a series of drone and missile attacks on Saudi Aramco's 400,000 barrels per day refinery complex in Jazan, as well as on storage facilities in Jazan and Abha on September 7–8. The facility has been shut down, and the coalition led by Riyadh has promised to "respond to the sources of threat." Simultaneously, the Houthis are engaged in clashes near the port of Mocha, advancing towards the Bab-el-Mandeb coast.
The significance of this front for global energy is challenging to overstate: after the closure of Hormuz, Saudi Arabia redirected exports via the East-West pipeline to the Yanbu terminal, through which over 90% of the kingdom's maritime shipments flowed in June. The embargo declared by the Houthis forced Asian shipments to be redirected through Suez, extending travel times by approximately 30 days and increasing freight costs. The threat to Yanbu represents a risk to the last major bypass channel for Middle Eastern oil.
European Gas Market: TTF Exceeds €80, Storage at 67% — Worst Winter Start in 15 Years
Front-month TTF futures traded at €80.3–80.8 per MWh (approximately $985 per thousand cubic meters) on Thursday, surpassing €80 for the first time since winter 2023. Since the beginning of the conflict, prices have risen by approximately 150%, and over 120% since the start of the year. The British NBP approached 200 pence per therm. Drivers for this increase include:
- attacks on tankers in the Persian Gulf and the continued halt of LNG exports from Qatar;
- expansion of the JKM–TTF spread, pulling spot cargoes to Asia;
- record low inventories: as of September 9, EU gas storage was filled to 67.33% (71.87 billion cubic meters) compared to a five-year average of around 84%.
The spread by country remains critical: Germany — around 53%, Austria — 67%, France — 71%, Italy — 83%. European operators are injecting gas at record rates but at the highest prices in four years. In contrast, the American market is seeing Henry Hub drop below $2.8 per million BTU — transatlantic arbitrage for U.S. LNG exporters has reached historic levels.
LNG and Coal: Atlantic and Coal Generation Close Qatari Gap
Damage to the Ras Laffan complex has knocked out approximately 17% of Qatar's export capacity; full recovery is estimated to take up to five years, resulting in a loss of approximately $20 billion in revenue per year. In the wake of Hormuz, about 15 laden LNG tankers are idling, with another two loading at the port — the market perceives the return of empty vessels home as a potential preparation for resuming shipments, but without passage through the strait, it remains a signal rather than a delivery.
For the coal sector, the LNG crisis presents an unexpected demand window. The volume of switching from gas to coal in Europe and Asia is estimated at 40–60 million tons; power production from coal stations in South Korea increased by nearly 40%, and in Japan by more than 11%. Newcastle prices are holding around $130 per ton, supported by disruptions in Indonesian supplies, while global coal demand in 2026 could rise by about 3% — to 9.1 billion tons.
Oil Products and Refineries: Refining Margins Increase, Russia Manually Controls Domestic Market
The global market for middle distillates remains the tightest segment: the shortage of diesel and aviation fuel in Asia and Europe supports crack spreads at multi-year highs, while fall maintenance schedules at U.S. refineries temporarily reduce supply. The shutdown of Jazan removes over 200,000 barrels per day of diesel and naphtha export volumes from the market.
In Russia, the domestic oil products market operates manually:
- The complete ban on gasoline exports has been extended to January 31, 2027, with the regulatory limit on exchange sales reduced to 10% (of which 8% are direct trading), effectively leaving the free market with only about 2% of output;
- Exchange indices are paradoxically decreasing despite the shortages: on September 8, the average price of Ai-92 on the SPbMTSB was 69.2 thousand rubles/ton, Ai-95 at 71.8 thousand rubles/ton with a trading volume of 11.6 thousand tons per session — three times lower than normal;
- The reason is delays in shipments for exchange contracts by months due to refinery downtime following drone attacks; the price gap between baselines reaches 25 thousand rubles/ton;
- The deficit is compensated by marine imports of gasoline from India, amounting to up to 400 thousand tons per month.
Electricity and Renewables: Energy Transition as the Only Predictable Trend
Amidst the raw materials chaos, the structural shift in the electricity sector is accelerating. Global electricity demand is expected to grow by 3.6% in 2026, supported by data centers, electric transportation, and air conditioning, while renewable sources will overtake coal in global output for the first time. Solar generation is adding approximately 600 TWh and moves to second place after hydropower. However, short-term vulnerabilities persist: in Europe, wind contribution dipped below 15% of demand at the beginning of the week, directly translating into rising gas and electricity prices. Each euro increase in TTF enhances the economics of storage, network investments, and long-term contracts for "green" electricity.
Calendar: What Energy Sector Participants Should Watch on Friday
- The market's reaction to the monthly OPEC report and the postponed weekly statistics from the U.S. Department of Energy on oil, gasoline, and distillate inventories.
- U.S. inflation data for August: commodity shocks increase the likelihood of a tightening rhetoric from the Fed, which restrains speculative demand for oil.
- Statements from the coalition on Yemen and any signals regarding the state of the Yanbu terminal.
- Dynamics of injection into European gas storage and the JKM–TTF spread as indicators of competition for spot LNG.
- Weekly results on the SPbMTSB and decisions by Russian regulators regarding exchange regulations and fuel imports.
Conclusions and Risks for Investors and Energy Sector Companies
- Oil. The $100 level has shifted from resistance to support; the range of scenarios for the quarter — from $85 with de-escalation to $120 with new attacks on vessels and Red Sea infrastructure.
- Gas. Europe enters the heating season with historically low inventory levels; in a cold winter, TTF quotes above €90–100 per MWh become a baseline rather than a stress scenario.
- Coal. Northeast Asia and parts of Europe will maintain elevated coal consumption until Qatari LNG production is restored — at least until spring 2027.
- Oil Products and Refineries. Crack spreads sustain margins for refiners outside conflict zones; in Russia, profits are being redistributed from independent gas stations to vertically integrated companies.
- Renewables and Electricity. Long-term capital flows into solar and wind generation, storage, and networks remain the only stable investment idea amid geopolitical volatility.
The day's conclusion for global oil, gas, and energy markets: two maritime chokepoints — Hormuz and Bab-el-Mandeb — are both under fire, and their status, rather than OPEC+ quotas or macro statistics, will dictate the prices of oil, gas, and electricity in the coming weeks. For energy sector market participants, scenario planning, logistics supply diversification, and hedging discipline are critically important.