Oil market: Brent retreats from highs on expectations of talks
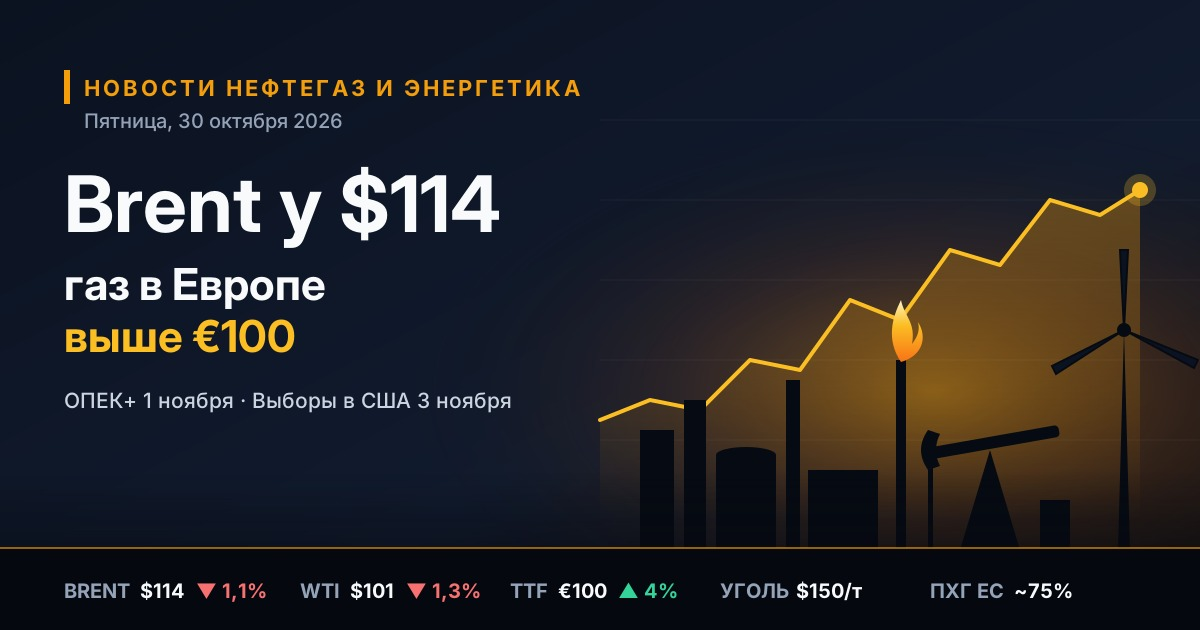
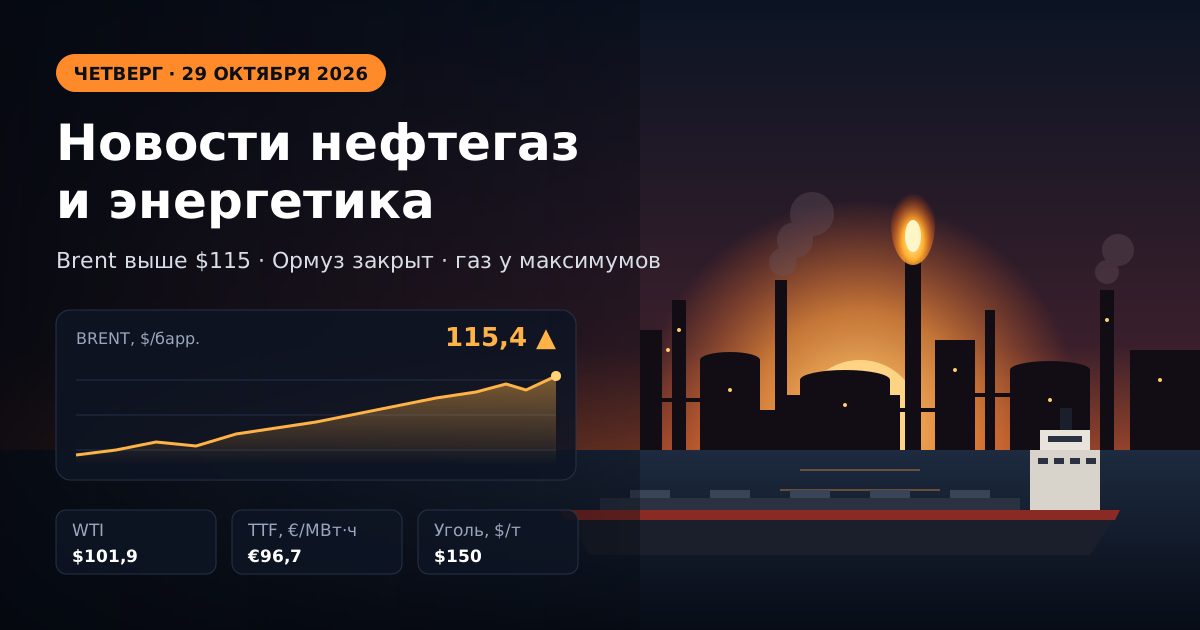
On Thursday, oil prices fell by about 1%. North Sea Brent slipped to $114 per barrel after closing Wednesday around $115.3. US WTI is trading around $101. The trigger for the correction was reports of Washington's attempt to resume peace talks with Tehran. The Iranian side said it is open to diplomacy and ready to accelerate the seven-day peace plan under discussion.
Key price benchmarks for the oil market:
- Brent: around $114/bbl, up almost 78% year-on-year;
- WTI: around $101/bbl, the Brent–WTI spread has narrowed to about $12.6;
- 52-week Brent range: from $58.7 (December 2025) to $120.9 (end-April 2026);
- Urals: around $111–112/bbl after a decline amid the broader correction.
The war premium, however, remains in place. The market is pricing in two threats: a possible US military operation against Iran after 3 November and an escalation of Houthi attacks on Saudi Arabia. That is why, even on positive diplomatic news, oil is holding above $110.
Middle East: attacks on refineries and threat to supplies
The security of infrastructure in the Persian Gulf remains the main source of volatility. On 27 October, the Houthis claimed a missile strike on Ras Tanura — Saudi Arabia's largest refinery. Riyadh has not officially confirmed the attack, although a fire was contained in the area of the terminal. On Thursday, the Saudi-led coalition reported intercepting a ballistic missile fired towards the kingdom's eastern provinces.
For refined products market participants, this means:
- continued risks to the export capacity of the largest raw material supplier;
- heightened volatility in refining margins in the Middle East and Asia;
- rising insurance and freight rates on tanker routes in the region.
OPEC+: quotas on paper and an actual supply deficit
On Sunday, 1 November, seven key OPEC+ countries will hold their next online meeting. The participants are Saudi Arabia, Russia, Iraq, Kuwait, Kazakhstan, Algeria and Oman. For November, the alliance has already kept production targets unchanged: 10.5 mln bpd for Saudi Arabia and 9.9 mln bpd for Russia.
The key problem is that the quotas exist largely on paper. In August, these seven countries produced about 25 mln bpd. That is roughly 5 mln bpd below the pre-war February level. Gulf countries' exports fluctuate within 60–80% of the norm. Alliance sources indicate that serious changes in production policy are unlikely before 2027. The review of production capacities, on which future quotas depend, has been postponed because of the war.
US inventories: strategic reserve at lowest since 1982
According to EIA data, US commercial crude inventories fell by 1.89 mln barrels in the week to 23 October, to 410.6 mln barrels. The situation with the Strategic Petroleum Reserve (SPR) is even more telling. Its stocks have dropped to about 283 mln barrels. This is the lowest since October 1982 and less than 40% of design capacity. The drawdown is linked to Washington's commitment to release 172 mln barrels to stabilise prices. The US's ability to smooth out new shocks through reserves is becoming increasingly limited.
Gas and LNG: Europe enters winter with record-low inventories
The European gas market is going through its most stressful period since 2022. On 28 October, the front-month TTF futures contract rose intraday to €100.9/MWh. For comparison: in February, before the conflict began, gas cost around €30. EU underground storage facilities are about 75% full. This is the lowest figure for this time of year since 2009, whereas the five-year norm is around 89%. Brussels has already relaxed the UGS filling target from 90% to 80%.
Key factors in the gas market:
- Qatar: about 17% of Ras Laffan's export capacity has been knocked out for years;
- Asia: spot LNG costs over $30/MMBtu, and Europe is competing with Asian buyers for every cargo;
- US: Henry Hub remains around $3/MMBtu — a gap with European prices of almost tenfold, which supports US LNG exports.
Power and renewables: wind keeps prices in check
Despite expensive gas, wholesale electricity prices fell in most European markets in the week to 19 October. The main reason is high wind generation. In France and the Netherlands, weekly prices dropped by 29%. On 23 October, France set an absolute record for wind generation for an October day — 415 GWh. Renewable energy is proving its role as a price stabiliser. At the same time, analysts expect electricity prices to rise this week as wind weakens and heating demand grows. Gas-fired generation will again set the marginal price.
Coal: the gas shock brings demand back
Thermal coal is one of the main beneficiaries of the LNG market crisis. The Australian Newcastle benchmark is trading around $150 per tonne. This is about 40% above the level at the start of the year, and on 6 October the price reached $152.2 — a high since autumn 2024. Power companies in Asia and Europe are switching from expensive gas to coal, which supports exporters from Australia, Indonesia, South Africa and Russia.
Russian oil exports: expensive freight and competition in Asia
Seaborne Russian oil exports averaged 3.55 mln bpd in the four weeks to 25 October — the lowest in five weeks. In the last week, by contrast, shipments rose to 3.85 mln bpd. Weekly export revenue is holding at around $2.6–2.8 bln.
Main trends in the export structure:
- Urals freight from western ports to India has reached a record ~$30 per barrel;
- in September, supplies to China rose to 1.68 mln bpd, while those to India fell to 1.8 mln bpd;
- Indian refineries are partly switching to oil from Iraq, Saudi Arabia and Brazil.
Refined products in Russia: export ban and market stabilisation
Russia's domestic fuel market is gradually emerging from the crisis. A temporary ban on exports of petrol, diesel and bunker fuel is in force from 1 August 2026 to 31 January 2027. A separate deadline at the end of October applies to producers of diesel and bunker fuel. The market is awaiting a decision on the future export regime. After the attack on the Ryazan refinery on 15 October, no new confirmed strikes on Russian refineries have been recorded. The average retail fuel price by mid-October was around 78.7 roubles per litre. Petrol imports from Belarus, India and Kazakhstan will continue at least until the end of the year.
Outlook and calendar: what investors should watch
In its updated forecast, the World Bank expects energy prices to rise by about 32% in 2026 and fall by 12% in 2027. This is a scenario of gradual supply normalisation. In the coming days, the fuel and energy market will be guided by the following events:
- 30 October — month-end close on commodity exchanges and US rig activity data;
- 1 November — meeting of the seven OPEC+ countries on December production;
- 3 November — US midterm elections, after which the risk of a military escalation around Iran increases;
- early November — gas withdrawal dynamics from European UGS facilities as the heating season begins.
The oil and gas markets remain in "headline" trading mode, where a single news item can move prices by several percent. For oil companies, refineries, traders and power utilities, this means high returns alongside significant risks. Hedging and liquidity management are becoming the main priorities until the end of the year.