Oil Market: Brent Hits Five-Month High
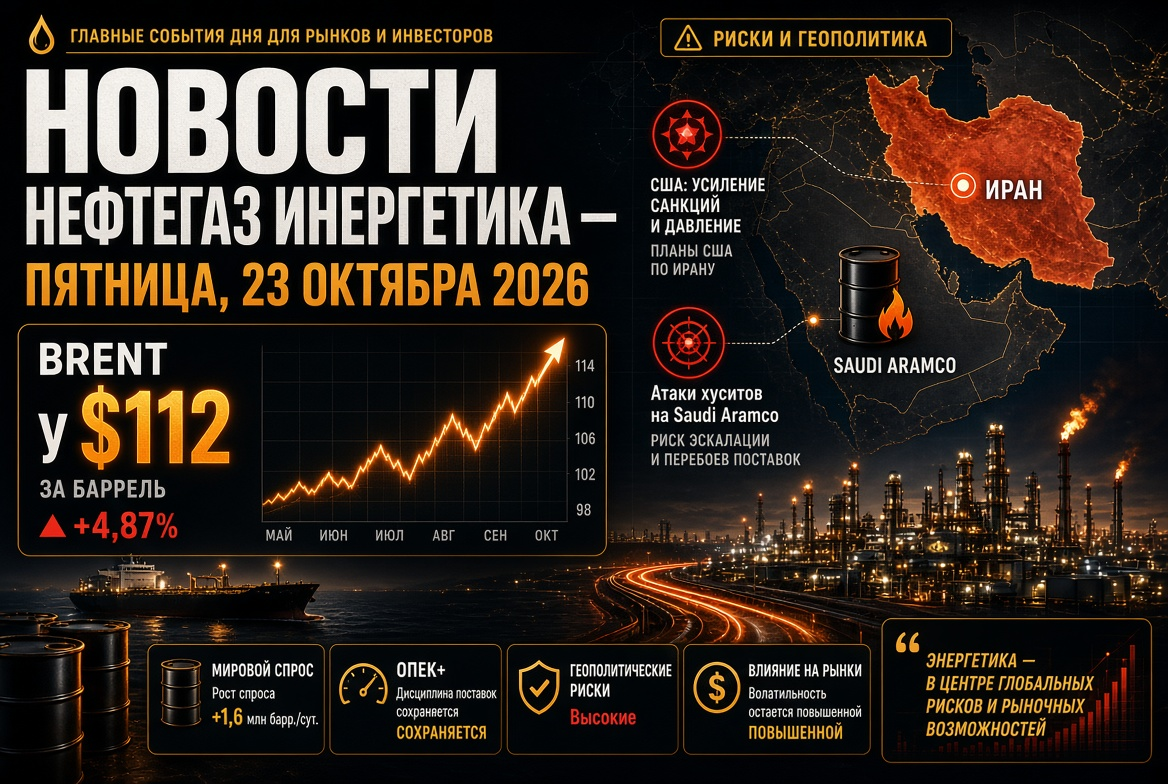
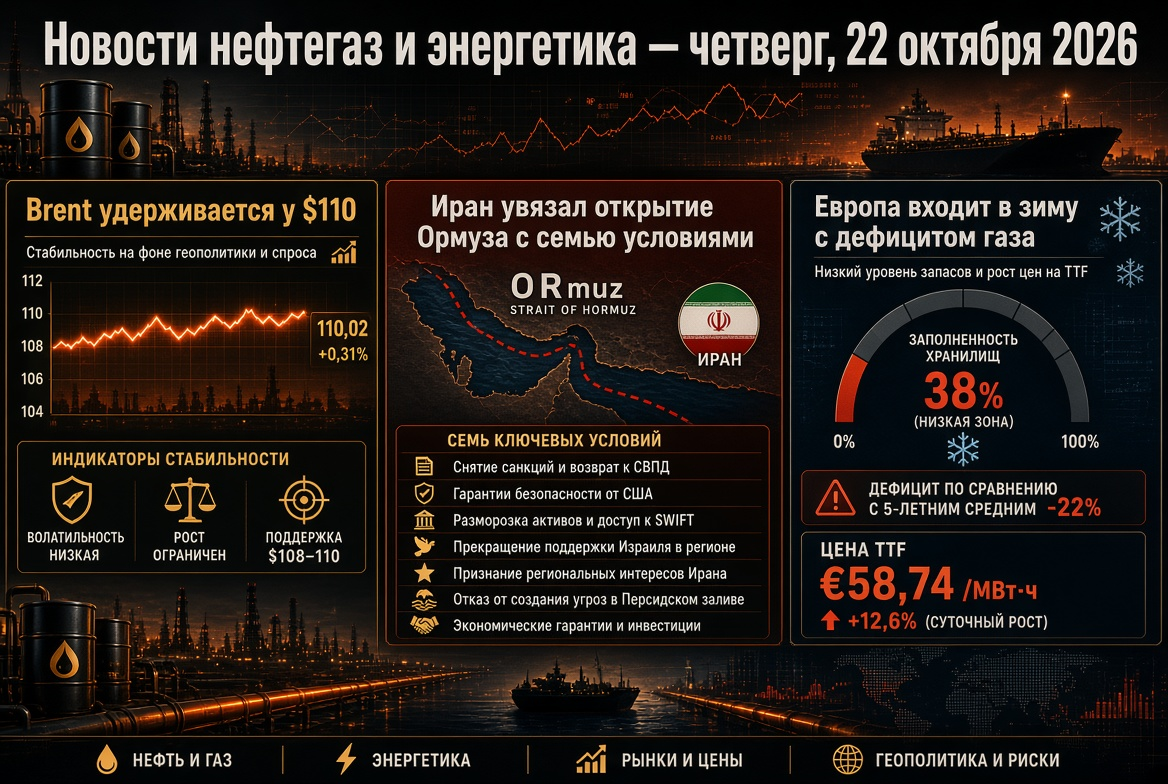
Brent's December futures traded in the range of $109–111 per barrel on Tuesday. The November WTI contract hovered around $99–100. Since the beginning of October, oil prices have risen by approximately 10%; on October 1, Brent was priced around $100. Oil prices are influenced by three main factors:
- Geopolitical Premium. Traders are factoring in the risk of supply disruptions from the Persian Gulf and the Red Sea.
- Declining Inventories. According to the EIA, for the week ending October 9, US commercial crude oil inventories fell by 8.6 million barrels to 415.6 million. Distillate stocks dropped to 102.6 million barrels, approximately 12% below the five-year average.
- Conflicting Flow Estimates. US Energy Secretary Chris Wright reports that oil shipments from the Persian Gulf have recovered to about 80% of pre-war levels. Ship-tracking analysts noted a sharp decline in transit through the Strait of Hormuz last week.
Middle East: Attacks on Saudi Aramco and Threat to Shipping
The main topic for the oil market today is the expansion of conflict within Saudi Arabia. Houthis claim to have attacked Saudi Aramco facilities in Yanbu on the Red Sea coast, the Shaybah field, airports in Riyadh and Abha, as well as military targets. Previously, the headquarters of Aramco in Dhahran was targeted. Riyadh has postponed the FII investment forum to next year.
The situation in the maritime corridor is also deteriorating:
- In the past two weeks, at least 18 vessels have been attacked;
- A tanker detonated on a naval mine in the southern part of the Strait of Hormuz;
- Daily oil transit through the region last week dropped to about 8.5 million barrels, down from over 20 million the week prior.
For the market, this means high volatility: any confirmation of damage to Aramco's production or export facilities could quickly add several dollars to the price.
OPEC+ and IEA: Quotas on Hold, Shortage Expected Until Year-End
Seven key OPEC+ participants have maintained their production targets for November unchanged. Saudi Arabia's quota stands at 10.5 million barrels per day, Russia's at 9.9 million, and Iraq's at 4.4 million. The increases agreed upon in 2026 largely remain on paper. In August, the group produced around 25 million barrels per day, which is approximately 5 million below pre-war levels. The next coalition meeting is scheduled for November 1.
Key takeaways from the IEA's October report:
- Global oil demand will decrease by 2.6 million barrels per day by 2026.
- Global supply will drop by 5.8 million barrels per day by 2026.
- The market balance will remain deficit until the end of the year.
- A shortage of middle distillates will persist until 2027.
Petroleum Products and Refineries: Diesel Remains the Most Scarce Commodity
The petroleum products segment is experiencing a double shock: disruptions in finished fuel exports from the Middle East coincide with damage to refineries in Russia. The IEA has approved the release of over 20 million barrels of diesel from reserves. In total, approximately 330 million barrels have already been sent to the market as part of the crisis response plan. Global diesel exports in September were about 700,000 barrels per day lower than last year. US refineries are operating at about 93.5% capacity, supporting high refining margins and profits for independent refiners.
Russia: Urals Discount Grows, Infrastructure Under Threat
Russian oil exports are under pressure from multiple fronts:
- Competition for Sales Markets. The discount on Urals at Baltic ports has widened to $20.85 per barrel compared to Dated Brent. This is due to weakening demand in India as Middle Eastern volumes return and high freight costs. Urals shipments from the Baltic fell by 21.9% over the week.
- High Tax Base. The price of Urals for calculating the crude oil export tax in October is around $104.7 per barrel compared to $92 in September, significantly above the budgetary target of $59.
- Logistics Attacks. On October 18, drones attacked the Saint Petersburg oil terminal with an annual capacity of 12.5 million tons and the "Ruchyi" oil depot.
- Domestic Market Regulation. The ban on gasoline exports is in effect until January 31, 2027. Restrictions on diesel exports for producers have been extended until the end of October. Data on refinery utilization has been classified under a decree dated September 28.
Gas and LNG: Europe Enters Winter with Storage Deficits
The Dutch TTF hub is trading around €88 per MWh. Since the beginning of the year, the price has increased more than threefold. Gas storage facilities in the EU are about 74% full, while the average for mid-October is around 86%. The market is further supported by three factors:
- The absence of Qatari LNG in the global market;
- An unplanned shutdown of Norway's Kårstø gas processing plant;
- The EU ban on the import of Russian LNG coming into effect in January.
The primary supplier filling in the lost volumes has been American LNG exporters. However, Europe is forced to compete for every shipment with Asian buyers.
Coal: Renaissance Amid the Gas Crisis
Energy coal has once again become a safety fuel for Asian power systems. The Australian Newcastle benchmark is holding steady around $150 per ton. This is about 40% higher than at the beginning of the year and 45% higher than last year. On October 6, the price reached $152.2, the highest since October 2024. A specific risk to the industry is the Australian High Court's ruling: upon approving coal mine expansions, regulators are now required to consider emissions from burning coal abroad. Mining companies warn that this may slow down investment.
Electricity and Renewables: Renewable Energy as a Price Buffer
The energy crisis has accelerated the development of renewable energy sources. In June, solar generation became the largest source of electricity in the EU for the first time, accounting for about 25% of production, or 52 TWh. In Germany, renewables made up 61.8% in the first half of the year. According to the industry association SolarPower Europe, following the onset of the Middle Eastern crisis, solar energy has saved the EU approximately €20 billion on gas imports. Onshore wind energy auctions are oversubscribed: in Germany, 2.5 GW has been allocated at an average price of around €50.6 per MWh. However, during the winter, with weak solar generation, electricity prices in Europe will again be tied to expensive gas.
What Energy Market Participants Should Monitor on Wednesday, October 21
- EIA's Weekly Report on US Oil and Petroleum Product Stocks. Particular attention should be given to distillates and refinery utilization.
- Reports from Saudi Aramco and Saudi Arabia's Ministry of Energy. It is important whether damages in Yanbu and Shaybah will be confirmed.
- Data on tanker transit through the Strait of Hormuz and freight rates.
- Dynamics of TTF and gas injection rates in European storage facilities.
- Russia's government decision on diesel exports starting in November.
- OPEC+ signals ahead of the November 1 meeting and the progress of production capacity audits.
Overall, the global oil and gas market remains a seller’s market: the fundamental deficit is being exacerbated by geopolitics, and petroleum product inventories are declining. For investors, this means maintaining high volatility in the coming weeks. Positions of refiners, LNG exporters, and coal mining companies appear to be the most resilient in this context.