Key agenda topics for venture investors and funds on Wednesday, October 21, 2026:
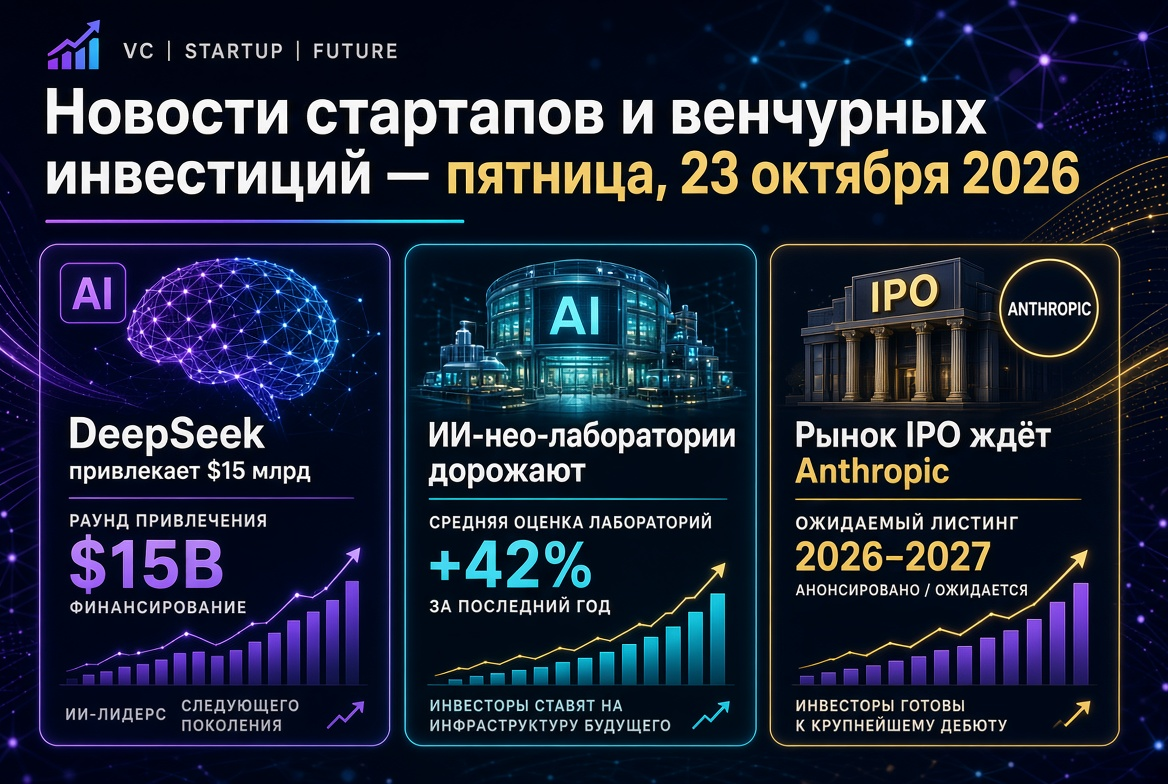
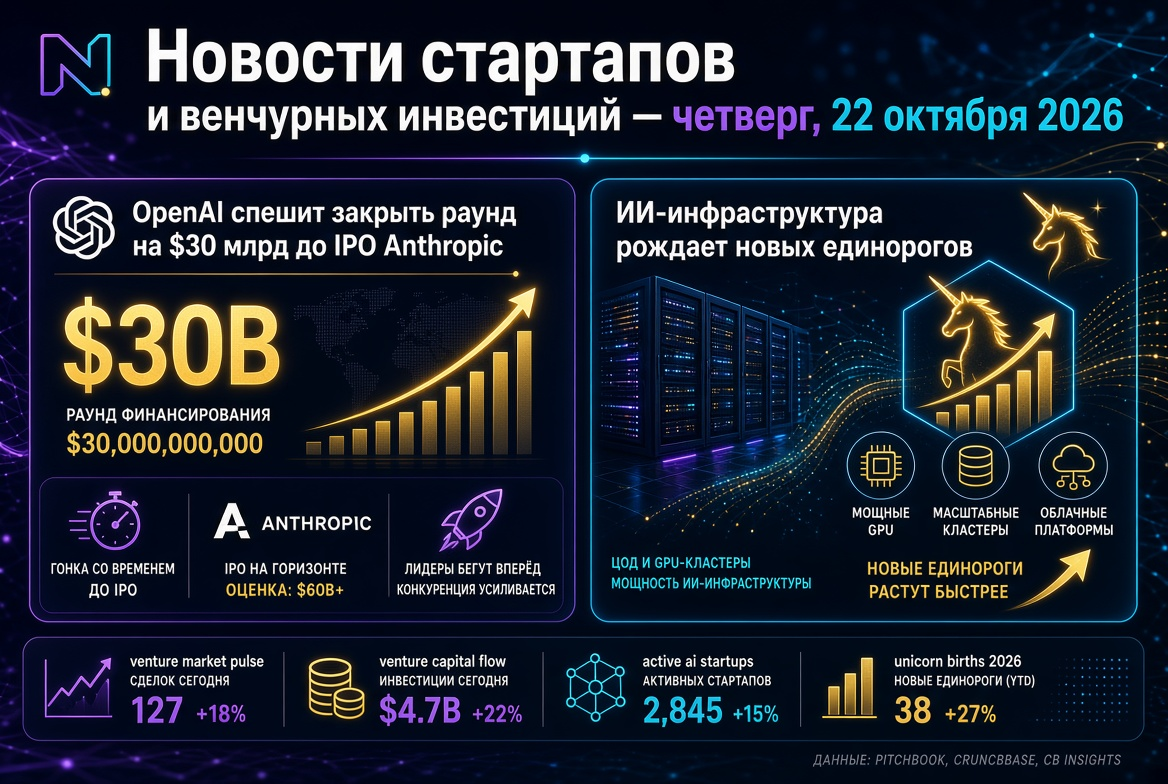
- OpenAI is aiming to raise approximately $30 billion at a valuation of over $1.4 trillion ahead of the anticipated IPO of Anthropic, expected in mid-November.
- AI infrastructure remains a key magnet for venture capital: Modal, Nscale, and Verda have closed significant funding rounds.
- New unicorns: Town has reached a valuation of $1 billion, and Dream Labs secured $90 million for robotics.
- Fintech and defense technologies are demonstrating sustained demand from funds.
- Market risks: corrections in the semiconductor sector and the debt burden of data centers are holding back valuations.
OpenAI vs. Anthropic: Battle for Institutional Capital
The most talked-about story of the week is OpenAI's attempt to secure a $30 billion funding round at a pre-investment valuation of $1.4 trillion. According to sources, current shareholders SoftBank and Abu Dhabi's MGX are involved in the negotiations, while UAE funds are collectively discussing an investment of up to $10 billion. Interest is also being shown by BlackRock and the University of California endowment.
Why OpenAI is Rushing
- Competition for Funds. Anthropic held an investor day on October 14 and is preparing for its listing; both companies are targeting the same sovereign funds and long-only investors.
- Infrastructure Commitments. The companies need a liquidity buffer in case a softening IPO market delays their own offering, scheduled for 2027.
- Valuation Growth. The $1.4 trillion valuation is approximately 64% higher than the March round at $122 billion, which had a $852 billion valuation and corresponds to a multiple of about 28x annual revenue of $50 billion.
For the venture market, this is a signal: after Anthropic publishes its earnings report, both companies will be valued relative to each other, and these numbers will set benchmarks for the entire generative AI segment.
AI Infrastructure: Mega Rounds and Revenue Above $1 Billion
The third week of October was marked by significant infrastructure deals. Investors are increasingly distinguishing between applied AI and “picks and shovels” — computational platforms with proven revenue streams.
- Modal Labs — D series round of $750 million led by Accel at a valuation of $15.75 billion; the company’s annual revenue has surpassed $1 billion.
- Nscale — a convertible round of $3.4 billion led by Third Point Ventures, the largest deal of the month.
- Verda — the Finnish GPU cloud provider raised $189 million in a B series round led by Emergence Capital at a valuation of over $1 billion; annual revenue is approximately $165 million with positive cash flow.
- Salience Labs — $125 million in a B series for photonic computing.
New Unicorns and Applied Artificial Intelligence
Despite the concentration of capital among leaders, applied-level startups continue to secure funding — provided they solve costly corporate problems.
Deals from Early in the Week
- Town — $108 million at a $1 billion valuation: the company is developing AI assistants that can operate at the level of entire teams.
- Dream Labs — former NVIDIA researchers raised $90 million to create a general AI "brain" for low-cost robots.
- Legora — $550 million in a D series at a $5.55 billion valuation; legal AI has established itself as one of the strongest verticals of 2026.
- Plinto — €2.9 million pre-seed for AI agents to control errors in billing.
Defense Technologies and Cybersecurity
Defense tech has officially transitioned from a niche segment to mainstream venture capital. Shield AI raised $1.5 billion in a G series at a valuation of $12.7 billion, while Anduril held a tender for employees at $1.3 billion, during which the company’s valuation jumped from $61 billion to $90 billion in just five months.
In cybersecurity, Armadin stands out: $255 million in a B series led by Andreessen Horowitz and Accel at a valuation of $2.5 billion for an autonomous offensive security platform. Investors are betting on protection against AI-augmented attacks.
Fintech: 35% Growth and Tokenization
The fintech sector is experiencing a strong recovery. Global investments in the industry in Q3 2026 amounted to approximately $27.5 billion across 897 deals — a 35% increase compared to the previous year.
- Ramp — $1.85 billion at a $60 billion valuation, one of the largest fintech rounds of the year.
- Valon — $150 million in a D series at a $2.3 billion valuation with participation from Ribbit Capital.
- Spiko — $90 million in a B series led by NEA to scale tokenized money market funds.
- Capitolis — $120 million in an E series.
Crypto venture remains cautious: in the first 18 days of October, crypto projects raised around $437 million across 27 rounds, with the main contribution stemming from the post-IPO round of Strive at $208 million.
Deep Tech, Biotech, and Climate Technologies
Venture funds continue to diversify their portfolios beyond AI applications:
- Oratomic — $475 million in a B series from a syndicate including ARCH Venture Partners, Khosla Ventures, Index Ventures, General Catalyst, and Bezos Expeditions.
- OMass Therapeutics — $310 million in a C series; Soufflé Therapeutics — $135 million in a B series for RNA therapy.
- Voltus — an oversubscribed D series round of $225 million for a distributed energy platform.
- Icon — $200 million in a D series for robotic construction with participation from Baillie Gifford and BlackRock.
New Venture Funds and Dry Powder
Capital raising continues, although it is concentrated among a limited number of managers. Notable funds from recent weeks include:
- Diffusion ONE — $1.25 billion;
- DCVC VII — approximately $654 million;
- TCGX Asia Life Sciences Fund I — $600 million;
- PSV Tech Fund II — $56 million for pre-seed startups in Northern Europe.
IPO Market and Valuation Risks
The year 2026 has already become record-breaking for tech IPOs, yet October's volatility has caused some issuers to pause their listings. Companies in the Philadelphia semiconductor index lost over $1.6 trillion in market capitalization in less than two weeks, and CoreWeave bonds with around $50 billion in debt experienced a sharp decline in value. AirTrunk REIT, Firmus, and SB Energy have postponed or withdrawn their listings, while bankers note that several companies are waiting for the results of the Anthropic listing.
Asia Remains Active
In India, the debuts of Zetwerk Manufacturing and Tonbo Imaging are expected this week, affirming the resilience of the exit window in emerging markets.
Russia and the CIS: Market in Search of a Bottom
The Russian venture market remains under pressure. In the first half of 2026, investments in tech startups amounted to approximately $29.3 million — a 62% decrease compared to the previous year, and the number of deals fell to 35. At the same time, capital is shifting towards M&A deals: 33 transactions valued at approximately $829 million. Investors prefer mature companies with proven business models and industrial B2B technologies.
Takeaways for Investors
The startup and venture capital market in October 2026 is displaying a two-speed dynamic. Capital is concentrating among leaders — AI labs, infrastructure, and defense technologies — while other companies must prove their revenue and unit economics. Key benchmarks for the coming weeks:
- results of the OpenAI round and final valuation;
- parameters and market reaction to the Anthropic IPO;
- dynamics of semiconductor stocks and debt market for AI infrastructure;
- pace of new venture funds being raised by the end of the year.
For funds, this is a period when discipline in valuations and diversification across sectors become more important than the speed of entering deals.