Daily Highlights: Key Events in Energy Sector
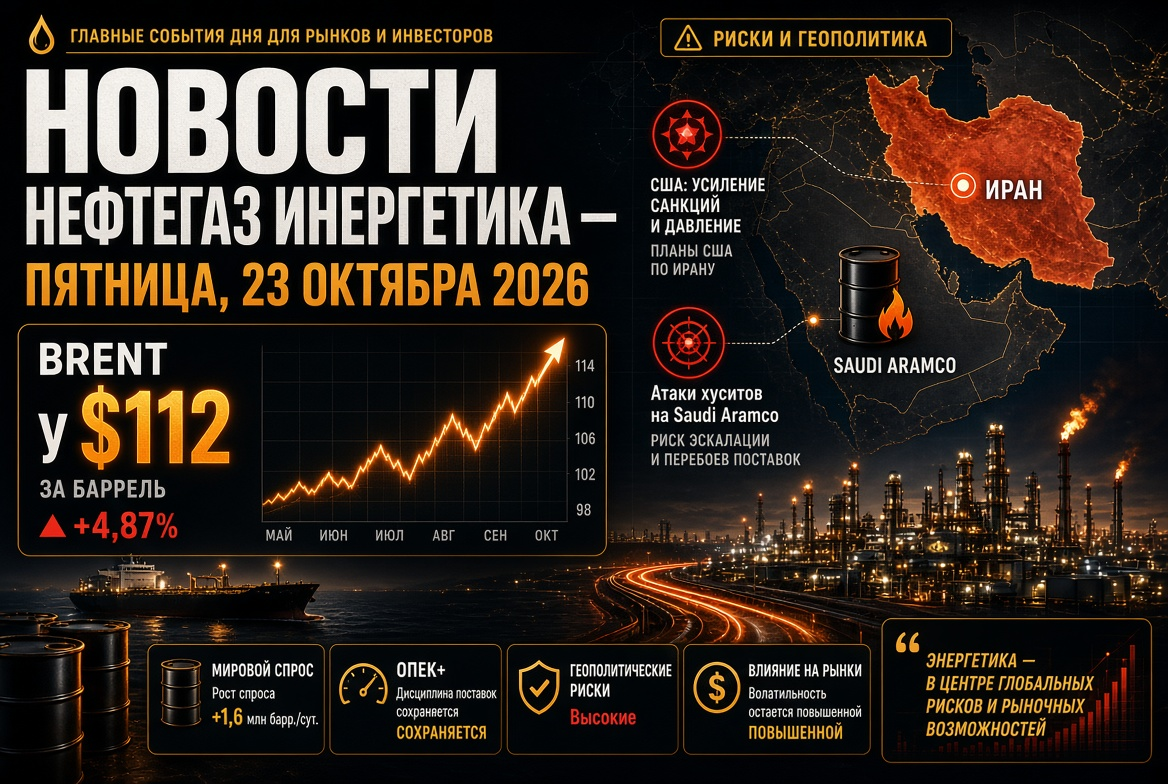
- Brent Oil rose approximately 3% on Thursday, reaching an intraday high of $112.68 per barrel; WTI briefly surpassed $100.
- The U.S. and Israel, according to American media, have prepared a plan for a "short but intense" operation against Iran following the midterm elections in November.
- The Houthis attacked Saudi facilities, including the Shaybah oil field run by Saudi Aramco; the U.S. State Department ordered the departure of some diplomats from Saudi Arabia.
- Gas in Europe: TTF is around €87/MWh, with storage filling levels approximately 75% against a seasonal norm of about 90%.
- Diesel Crisis: The diesel refining margin in Europe and the U.S. remains above $100 per barrel.
Oil Market: Brent at Highs Since May
The main driver of the oil market is the anticipation of a new phase of confrontations over Iran. Traders are assessing the likelihood of renewed strikes following the U.S. midterm elections set for early November. Simultaneously, the market is reacting to the Houthi attacks on Saudi infrastructure: a drone strike on the Shaybah oil field resulted in two fatalities, with one more killed at Dammam airport.
Fundamental data also supports prices. U.S. commercial oil inventories decreased by 3.06 million barrels last week against a forecasted decline of 0.8 million, although inventories at the Cushing hub increased by nearly 1 million barrels. Over the month, Brent has risen by more than 8%, and on a year-on-year basis, it has increased by approximately 70%.
A crucial signal for professional market participants is the divergence between paper and physical markets. Over the past two weeks, Brent futures have increased by about $10, while prices for physical crude oil have, conversely, been declining. This indicates that a significant portion of the rally is speculative and reflects the geopolitical premium rather than an acute shortage of crude.
Strait of Hormuz: Tehran's Seven Conditions
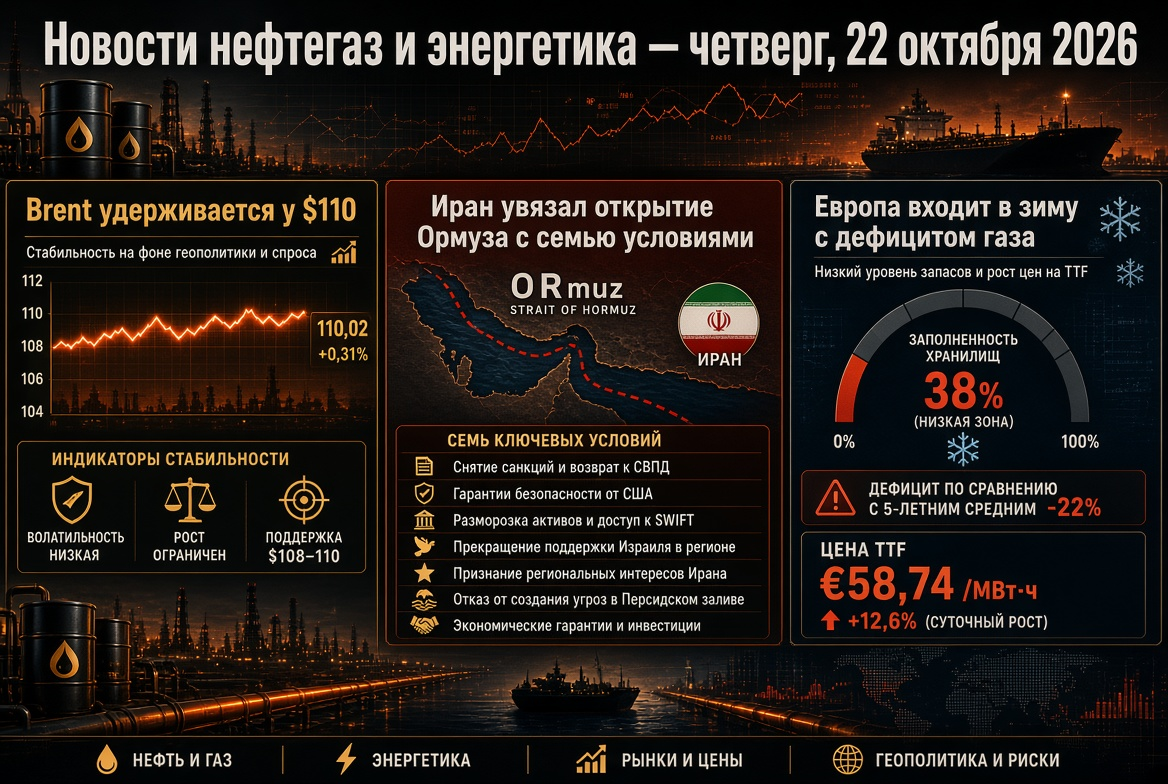
The situation in the Strait of Hormuz remains a key factor for global oil and LNG. Iranian authorities are tying the full reopening of the route to the fulfillment by Washington of seven conditions outlined in the so-called Islamabad Memorandum. Iranian Foreign Minister Abbas Araqchi stated that if the demands are met, the strait could be opened on the sixth day, and negotiations with the U.S. could be resumed on the seventh.
Physical flows have also partially recovered:
- Transit of crude oil through the strait is estimated at about 10.3 million barrels per day — around 76% of the pre-war level.
- The share of oil products in total cargo flow has dropped to 11% from over 20% prior to the conflict.
- Tehran and the IRGC threaten to extend restrictions to Bab-el-Mandeb and the Suez Canal, creating risks for tanker logistics between Asia and Europe.
OPEC+: Quotas on Paper, Production Below Targets
The OPEC+ alliance has kept its production targets for November unchanged. Saudi Arabia's quota stands at 10.5 million barrels per day, Russia at 9.9 million, and Iraq at 4.4 million. However, the actual production of seven key participants in August was around 25 million barrels per day — approximately 5 million below the pre-war level of February. The increases in quotas in 2026 have largely remained symbolic.
The next meeting of the alliance is scheduled for November 1. An audit of production capacities, necessary for allocating quotas for 2027, has been postponed due to the war, so significant changes in oil policy are not expected until next year. Russian Deputy Prime Minister Alexander Novak expressed confidence that OPEC+ will play a leading role in overcoming the crisis, noting the stability of Russian oil exports.
Oil Products and Refineries: Diesel Shortage
The most pressured segment currently is not crude oil but oil products. The diesel refining margin in Europe has exceeded $100 per barrel, while the historical norm is around $20. In the U.S., records above $117 have been reported in September. The reasons are structural:
- Downtime of some refining capacities in Gulf countries;
- Regular drone attacks on Russian refineries;
- Ban on diesel exports for Russian producers until October 31;
- Export restrictions on fuel by several other countries, including China.
For investors, this indicates sustained high profitability for independent refiners with operational plants, primarily in the U.S. American energy regulators expect diesel spreads to remain above historical averages until 2027.
Gas and LNG: Europe Enters Winter with Inventory Deficits
The European gas market remains one of the major risks of the season. TTF futures are trading around €87/MWh — levels unseen since early 2023. The filling rate of European underground storage facilities is about 74–75%, approximately 17 percentage points below the seasonal norm. The EU has already softened the mandatory target for filling from 90% to 80%.
The key issue is the shortage of LNG. Attacks on the Qatari Ras Laffan complex have knocked out two technological lines with a combined capacity of 12.8 million tons per year, and QatarEnergy has ruled out the construction of pipelines as an alternative to maritime exports through Hormuz. Europe and Asia are competing for spot cargoes of liquefied gas, and a cold winter could trigger a new price spike.
Russian Fuel Market: Export Restrictions
Russia continues to impose a ban on gasoline exports until the end of 2026, while for diesel fuel, restrictions for producers extend until the end of October. Mid-month signals emerged regarding a partial easing of oil product export restrictions, provided the domestic market is fully supported. Refineries are transitioning to winter diesel production, and authorities are monitoring reserve formation during scheduled maintenance. The decision on extending or easing export restrictions from November 1 will be a key event for fuel market participants.
Power Sector, Renewable Energy, and Coal
The energy crisis is accelerating the transition to renewable sources. According to the IEA, in 2026, renewables will surpass coal for the first time and become the largest source of global electricity generation. Renewable energy generation is expected to grow by more than 8%, with solar output increasing by about 600 TWh, surpassing wind generation. Global electricity demand is projected to rise by 3.6% in 2026, with increases of 5.5% in China and 7% in India.
At the same time, high gas prices are supporting coal generation in Asia and to some extent in Europe: energy systems are using coal as a buffer against LNG shortages. The thermal coal market remains elevated, and coal exporters maintain strong positions in the Asia-Pacific region.
Forecast and What to Watch for on Friday
In conclusion, the news on oil and gas and energy will primarily be determined by geopolitics as the week ends. Energy sector participants should pay attention to the following factors:
- Signals from Washington and Tehran regarding Iran and the Strait of Hormuz ahead of the U.S. elections.
- New Houthi attacks on Saudi oil infrastructure and shipping.
- The dynamics of the spread between futures and physical grades of oil as an indicator of the rally's sustainability.
- Decisions regarding the export of Russian oil products after October 31.
- Weather forecasts for Europe and the rate of gas withdrawal from UGS.
The baseline scenario anticipates Brent prices to remain in the range of $105–115 per barrel until early November. Analysts agree that de-escalation before the U.S. elections is not expected, thus the geopolitical premium in oil, gas, and diesel prices is likely to persist. A sharp correction is only possible with real progress in negotiations regarding Hormuz.