Key themes shaping the agenda for venture investors and funds as of October 16, 2026:
- Third quarter results. Capital is consolidating in megaraounds, and AI's share of global venture financing is approaching two-thirds.
- New decacorns in AI infrastructure. Modal Labs and Applied Intuition showcase multiple growth in valuations over a few months.
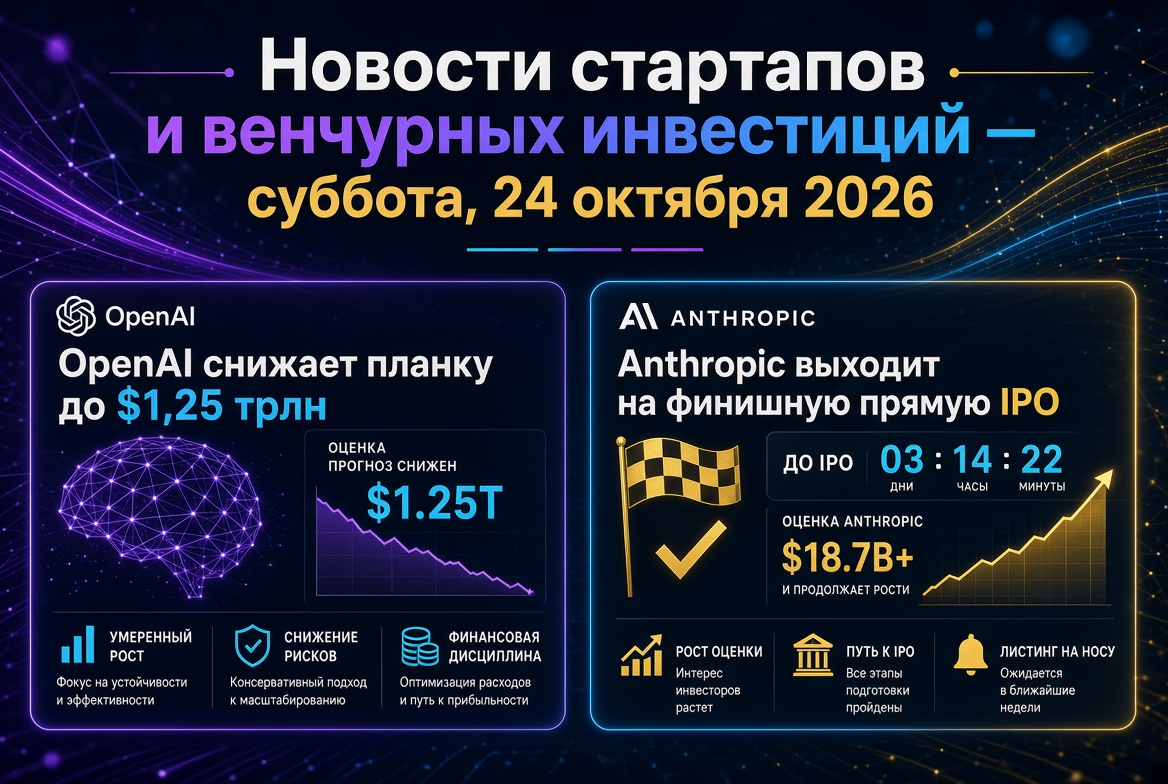
- Preparing for Anthropic's IPO. The market awaits the public S-1 form, timelines for which will dictate the November placement window.
- European deep tech. Photonics, energy storage, and state funds support the region's best quarter in four years.
- Early stages. Seed rounds totaling $50–60 million are becoming the norm for teams with a strong technology base.
Venture Market in Q3 2026: Less Money, More Megaraonds
According to Crunchbase, global venture funding in Q3 2026 amounted to $159 billion. Approximately 6,000 startups received funding. This is a 25% decrease from the record $212 billion in Q2, but 53% higher than the previous year. Over nine months, the volume of venture investments reached $679 billion, the highest recorded for this period in history.
The market structure changed more significantly than its volume:
- Record megaraonds. 27 companies raised $1 billion or more compared to 16 in Q2 and 14 in Q1. These deals accounted for roughly one-third of the total quarterly capital.
- AI dominance. Startups in the artificial intelligence sector received $102 billion, or 64% of global venture funding.
- Quarter leaders. Databricks and Safe Superintelligence raised $5 billion each, with another six companies securing at least $3 billion each.
- Early stages grow. Early-stage funding increased by 25% year-over-year to $40.6 billion. Seed rounds collectively raised $13 billion.
The concentration is also noticeable on the fund side. According to PitchBook and NVCA, in the first half, Andreessen Horowitz, Thrive Capital, and Founders Fund accounted for 48.1% of all capital raised by U.S. venture funds. The creation of first-time funds is at its lowest since 2016.
AI Infrastructure: Modal Labs Triples Valuation and Joins the Decacorn Club
The most discussed deal of the week is the Modal Labs round. The New York provider of server infrastructure for inference closes a round of $750 million led by Accel at a valuation of $15.75 billion. Just in May, the company was valued at $4.65 billion during its Series C round of $355 million. Therefore, its valuation has more than tripled in about four months.
The logic for investors is clear:
- Annual revenue for Modal exceeded $300 million last spring;
- Demand is driven by AI agents and tools for programming that require isolated execution environments;
- The pay-per-use model for actual computation time is suitable for uneven inference loads.
This deal confirms a thesis that funds are increasingly incorporating into their investment strategies: in 2026, the fastest repricing occurs at the "shovels and picks" level for the AI-agent economy.
Autonomous Systems and Defense Technologies: Applied Intuition Valued at $30 Billion
Software developer for autonomous transport, Applied Intuition, received investment offers with a valuation of at least $30 billion. This is double the $15 billion level recorded in the Series F round. A round exceeding $1 billion is likely in the coming months.
Key parameters for investors:
- The company works with 18 of the 20 largest global automotive manufacturers;
- A valuation of $30 billion corresponds to approximately 36 times annual revenues projected at $830 million for 2025;
- The rising multiplier is linked to the company's entry into military and off-road autonomy, where Applied Intuition competes with Anduril and Saronic.
In the same segment, Fortastra raised $30 million in a Series A round for maneuverable spacecraft aimed at orbital security. Developer of delivery drones Rino.ai closed a Series C round of $100 million.
Anthropic IPO: The Market Awaits Public S-1
The main question for the public offering market is the timing of Anthropic's IPO. The company confidentially submitted its S-1 draft form on June 1, shortly after its Series H round of $65 billion at a valuation of $965 billion. According to business press reports, Nasdaq has been chosen as the listing venue, with the target window shifting from October to November to allow investors to view third-quarter results.
If the marketing of the offering begins in the week of November 9, the public version of the prospectus should appear by the end of October. Market benchmarks for valuation are reaching $2 trillion. For venture funds, this deal is significant for three reasons:
- It will set the disclosure standard for the entire AI sector;
- It will serve as a test for late-stage valuations in the private market;
- A successful listing may open the exit window for other major AI companies.
Asia: Manus Raises $500 Million Following Deal Cancellation with Meta
AI-agent developer Manus (parent company of Butterfly Effect) has raised over $500 million. This is the first round after Chinese authorities compelled Meta to abandon its plans to acquire the startup for about $2 billion. The round was led by Boyu Capital and IDG Capital, with participation from Tencent, HSG, and ZhenFund. The valuation is not disclosed, but earlier reports indicated a target of around $4 billion. The company is also considering an IPO in Hong Kong.
This deal demonstrates that regulatory risks of cross-border M&A in the AI sector do not diminish local investors' appetite for agent platforms.
Europe: Deep Tech, Photonics, and State Funds
European startups raised approximately $25 billion in the third quarter. This is the region's best result in four years and represents a 77% year-over-year increase. October deals confirm a shift toward deep technologies:
- Skeleton Technologies (Estonia) received a nine-figure strategic investment from Siemens and joined the unicorn club. The company will allocate over $200 million to expansion and R&D in Silicon Valley focused on AI data centers.
- Salience Labs (Oxford) raised $125 million for optical switches that connect thousands of GPUs using light.
- Rabot Energy closed a $50 million Series B round to turn home batteries into a virtual power plant.
- British Business Bank supported Entrepreneurs First, Headline, and Evantic within a £180 million program for AI funds.
Seed and Early Rounds: New Norm for Checks
Early-stage funding is becoming progressively capital-intensive. Among the notable deals in recent days:
- Hone — a seed round of $60 million from Benchmark and Index Ventures at a valuation of $285 million for autonomous AI agents responsible for business outcomes;
- Sabi — seed rounds of $50 million led by Khosla Ventures for a wearable neurointerface;
- Oratomic — Series B of $475 million for fault-tolerant quantum computers;
- Arena — Series B of $200 million at a valuation of $3.1 billion from Lightspeed and Khosla Ventures, nearly double January's valuation;
- Multiply Labs — Series B of $75 million from Lux Capital for pharmaceutical manufacturing robotics;
- Matchpoint Therapeutics — Series B of $150 million for "molecular glue" based therapies.
Fintech is also maintaining activity. Valon Technologies raised $150 million at a valuation of $2.3 billion, Capitolis — $120 million in a Series E round, and Spiko — $90 million in a Series B round.
Russia: Cautious Market and Focus on Corporate Demand
The Russian venture market is moving against the global trend. According to the Moscow Venture Fund, in the first half of 2026, the volume of venture investments decreased by 48% to 4.6 billion rubles, and the number of deals fell by 45% to 54. High returns from risk-free instruments are diverting capital from startups, resulting in funding primarily going to B2B projects with clear revenue and corporate clients.
Support infrastructure, however, is expanding:
- The Moscow Venture Fund will allocate 250 million rubles to technology companies and expects to attract around 1 billion rubles in co-investments;
- FPRI launched a fund of 300 million rubles for startups in the information security sector.
What Investors Should Watch for Next Week
- Publication of Anthropic's S-1. Submission timelines will be the main indicator for the technology IPO market.
- Closure of Applied Intuition's round. The outcome will indicate whether the market is ready to pay a premium for dual-use autonomy.
- Money20/20 USA (October 18-21). The conference expects new fintech deals and partnerships.
- Oslo Innovation Week (October 19-23). A venue for announcements from the Nordic climate and deep tech venture space.
The venture market in 2026 operates under the principle of "fewer deals — larger checks." Capital is rapidly repricing AI infrastructure, while megaraonds and the preparation for the largest IPOs are forming a new system of benchmarks for valuations. For venture investors and funds, discipline is coming to the forefront: revenue, multiples, and a realistic path to exit are more important than the volume of the announced round.