Oil Market: Geopolitical Premium Keeps Brent Above $105
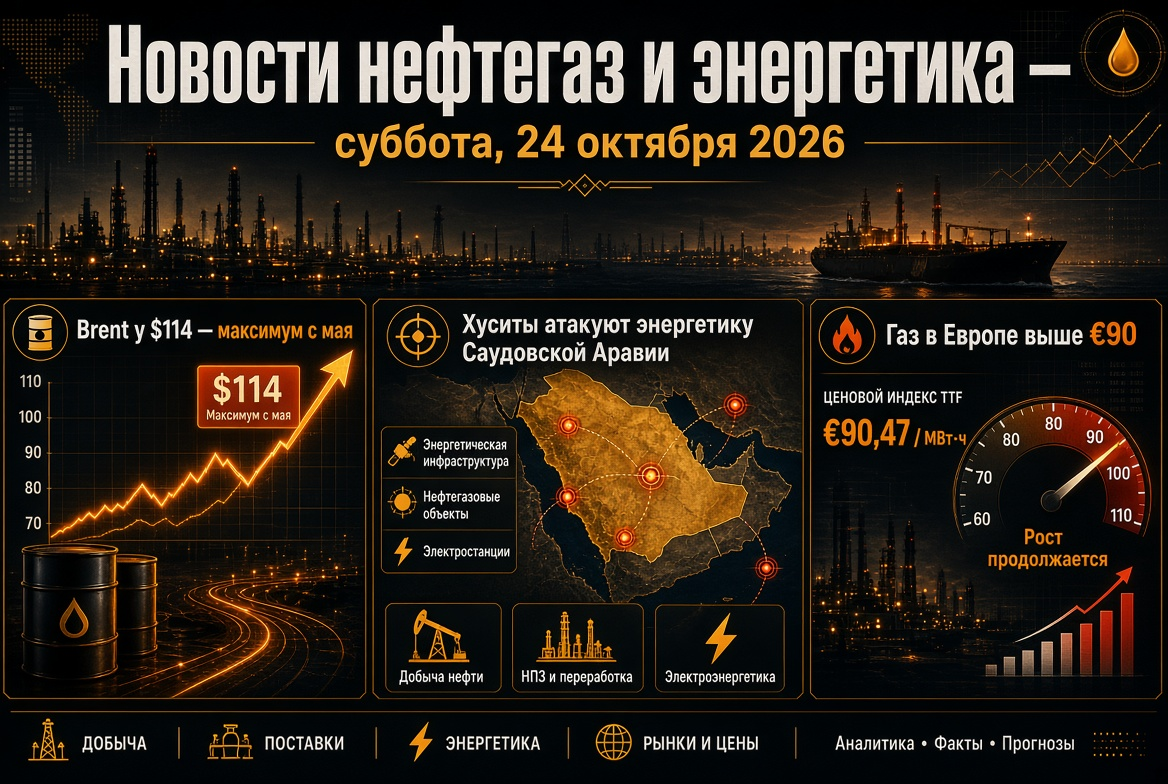
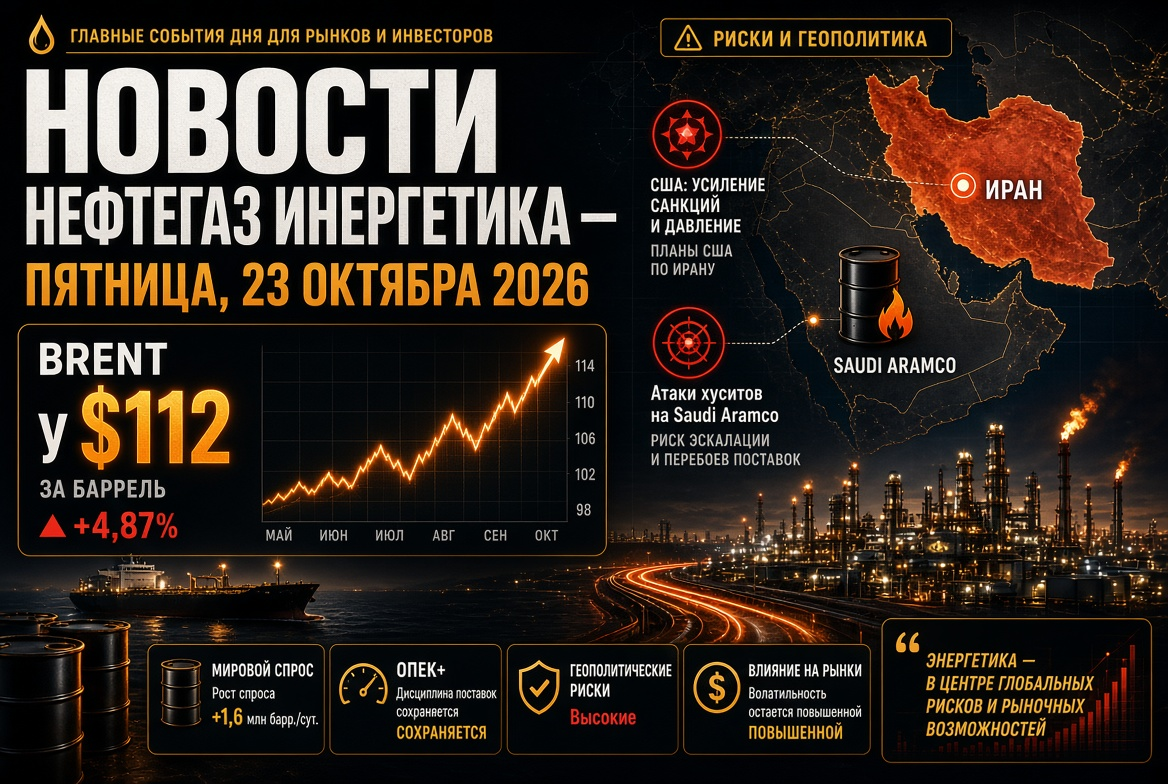
Following trading on October 14, the December futures for Brent were quoted around $106.3–106.5 per barrel, peaking at $107.15 during the day. American WTI is trading around $95. A year ago, oil was priced at approximately $62–63, indicating a growth of over 70% in twelve months.
Key price drivers include:
- Strait of Hormuz. Attacks on vessels continue: tankers traveling routes without coordination with Tehran are being struck by mines, with a container ship sinking at the strait's exit on October 13. Iran links the full reopening of the strait to the fulfillment of seven conditions set for Washington.
- Houthi Strikes on Saudi Arabia. The "Ansar Allah" movement announced attacks on Saudi Aramco facilities in Dhahran and the Eastern Province, as well as refining plants in Riyadh and the capital's airport, promising to expand their list of targets.
- Discrepancy Between Futures and Physical Market. Real physical cargoes are estimated at around $129 per barrel—significantly more expensive than paper Brent.
- Record Freight Rates. Delivering Russian oil from Baltic and Black Sea ports to India costs $27–32 per barrel, while shipping from Ras Tanura to Rotterdam has increased from about $2 in 2025 to over $35.
Analysts anticipate WTI fluctuations in the $90–100 range in the coming weeks; further escalation in the Middle East could push Brent back to spring peaks above $120.
IEA Report: Decline in Oil Demand Comparable to Major Crises
The October IEA report became the main analytical event of the week for the oil and gas sector. Key figures include:
- Global oil demand will decrease by 2.61 million barrels per day by 2026—down to 102.38 million b/d (forecast downgraded by about 110,000 b/d).
- Global oil supply will drop by 5.8 million b/d by 2026—down to 100.7 million b/d.
- A return to growth in consumption is not expected before March 2027; in 2027, demand will be around 104.38 million b/d, still below the 2025 level.
- The largest losses are expected in distillates and petrochemical feedstocks, particularly in Asia.
The IEA is also accelerating the release of strategic reserves: following a record decision in March to release 400 million barrels, the agency called on countries to expedite diesel fuel delivery from reserves to the market. OPEC, in turn, has lowered demand estimates for 2026 for the sixth consecutive time but raised forecasts for 2027, citing the need to replenish depleted stocks.
OPEC+: Quotas Frozen, Actual Production Below Target
Seven OPEC+ countries have kept targeted oil production levels unchanged for November. Quotas are distributed as follows:
- Saudi Arabia — 10.478 million b/d;
- Russia — 9.949 million b/d;
- Iraq — 4.431 million b/d;
- Kuwait — 2.676 million b/d;
- Kazakhstan — 1.628 million b/d;
- Algeria — 1.007 million b/d;
- Oman — 841,000 b/d.
In practice, quotas largely remain on paper: due to the war and logistical constraints, actual production by several participants is significantly below targeted figures. The structure of the alliance has changed following the exit of the UAE from OPEC and OPEC+ as of May 1, 2026. The next "seven" meeting is scheduled for November 1, with the monitoring committee meeting on November 29.
Russia-U.S. Diesel Deal: A New Factor in the Oil Products Market
The oil products market continues to adjust to the agreement reached on October 9 during a phone call between the presidents of Russia and the U.S. The U.S. Treasury issued a license temporarily easing sanctions on Russian diesel fuel. Deal parameters include:
- over 300,000 tons of diesel to American and global markets in October;
- an additional 500,000 tons in November and then around 1 million tons;
- potentially up to 3 million tons a month, depending on the state of Russian refineries.
Moscow is prematurely lifting restrictions on diesel exports. For Russian oil companies, this represents additional foreign currency revenues and an incentive for refinery utilization. For Washington, it serves as a tool to lower fuel prices ahead of Congressional elections. European diplomacy criticized the deal and announced new sanctions. The question of feasibility remains: following the strikes on refineries in the summer, some processing capacities are still being restored.
“Energy Truce”: A Fragile Pause for Infrastructure
On October 11, Donald Trump announced the commencement of an "energy truce" between Russia and Ukraine—a mutual cessation of strikes on energy infrastructure. The Kremlin described the idea as positive, though no official conditions were published. On October 12, strikes on Ukrainian energy facilities continued, and only on October 13 was the first day recorded without such attacks. For market participants, the resilience of the pause is critical: attacks on refineries are one of the factors contributing to global diesel shortages in 2026.
Gas and LNG: Europe Enters Winter with Supply Deficits
The European gas market is the most strained segment of the global energy sector. Futures at the TTF hub surged to €86–87 per MWh, a peak since December 2022; the year-over-year increase is around 170%. Reasons include:
- Falloff in Qatari LNG exports following damage to Ras Laffan facilities;
- EU underground storage is about 73% full, against a seasonal norm of around 90%;
- Acute competition with Asia for available liquefied natural gas cargoes.
Some analysts maintain a moderate outlook—around €56 per MWh in Q4, thanks to accelerated injections. However, physical constraints in the gas market are not alleviated by diplomatic statements. Notably, supplies of Russian Arctic LNG to European ports over the past nine months have increased by approximately 9.5%.
Coal: The Return of Asia’s Primary Fuel
The LNG deficit has made coal the primary beneficiary of the crisis. Newcastle thermal coal is trading at around $149–150 per ton, near three-year highs, with an increase of over 40% year-on-year. With LNG prices in Asia around $25 per MMBtu, high-quality coal costs generating companies roughly 80% less. The IEA expects record global demand for coal in 2026: China, India, Japan, South Korea, and parts of Europe are increasing coal generation. The fourth quarter is traditionally peak season for imports, so coal exports may significantly rise by year-end. In India, the number of power plants with fuel stocks below 25% of normal levels reached 85 as of October 1.
Renewables and Electricity: Record Generation and Network Challenges
The energy transition continues even amid oil and gas shocks. In 2025, renewable energy sources surpassed coal in global electricity production for the first time in a century. Recent records include:
- Australia: On October 11, rooftop solar generation in the country's main power grid reached 17.5 GW, with solar accounting for 72% of consumption;
- India: daily solar output set a record on September 30;
- USA: in May, solar generation first exceeded coal generation.
The downside—record constraints on renewable generation and negative electricity prices during peak sunlight hours—confirms that investments in energy storage systems and grid infrastructure are becoming key issues for energy companies.
The Russian Fuel Market: Stabilization under Regulator Oversight
The domestic oil products market in Russia remains in a phase of unstable stabilization:
- average retail gasoline price — 78.73 rubles per liter, diesel fuel — 86.72 rubles;
- since the beginning of the year, gasoline has risen by 21%, significantly outpacing overall inflation;
- on the exchange, AI-92 decreased to 69.4 thousand rubles per ton over the week, while AI-95 rose to 70.9 thousand rubles;
- the Federal Antimonopoly Service has signed pricing agreements on fuel with 35 regions.
The main risk—unscheduled refinery repairs: expanding diesel exports necessitates balancing external obligations with complete domestic market supply.
What Matters to Investors and Energy Market Participants
- Oil: The geopolitical premium remains; base range for Brent is $100–110 with risks of spikes from attacks on Gulf infrastructure.
- Oil Products: Diesel remains the most deficient product; Russian supplies and IEA strategic reserves may partially alleviate the premium.
- Gas: European prices are sensitive to weather and injection rates; a cold winter could push TTF above €100.
- Coal: Price support is expected to continue until year-end due to seasonal demand peaks in Asia.
- Key Dates: OPEC+ meeting on November 1 and data on oil and gas reserves in the U.S. and Europe.
Global energy in the fall of 2026 operates under simultaneous supply shocks and demand compression. For oil and gas companies, this is a period of high revenue and increased risks, for consumers — a time of expensive energy, and for the renewable sector and storage solutions — an opportunity for accelerated growth.