Key Highlights Ahead of Trading on October 22
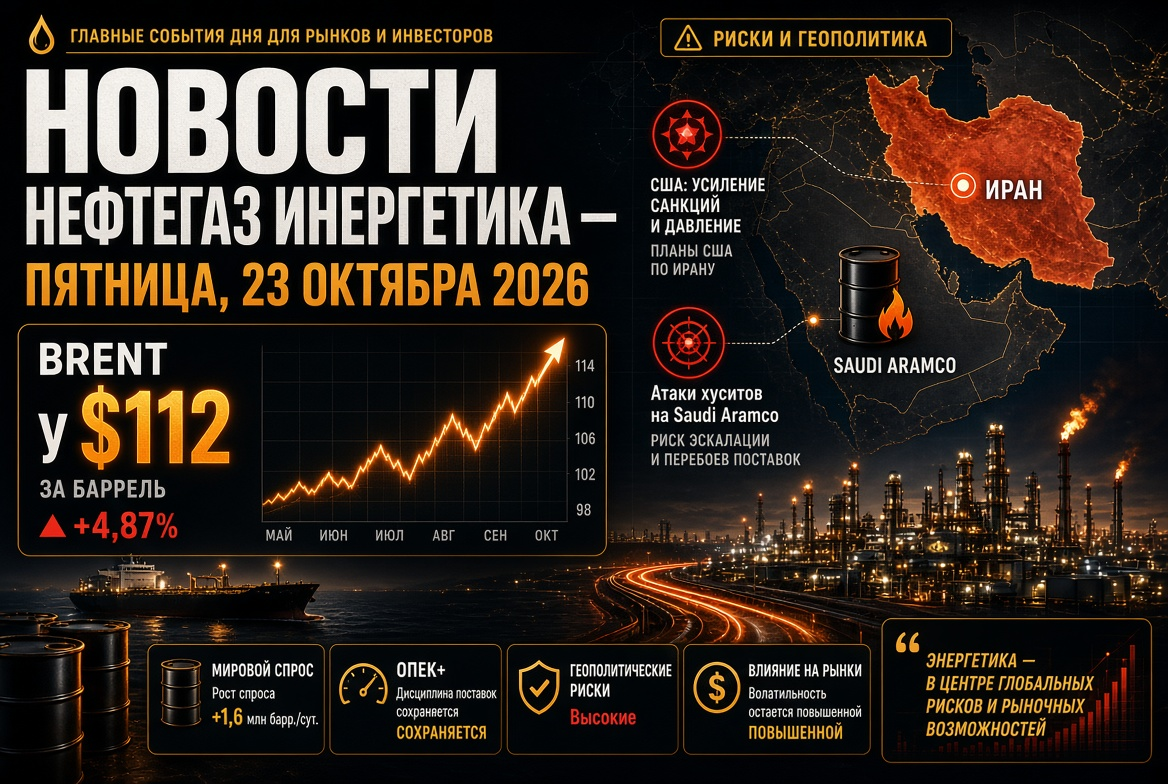
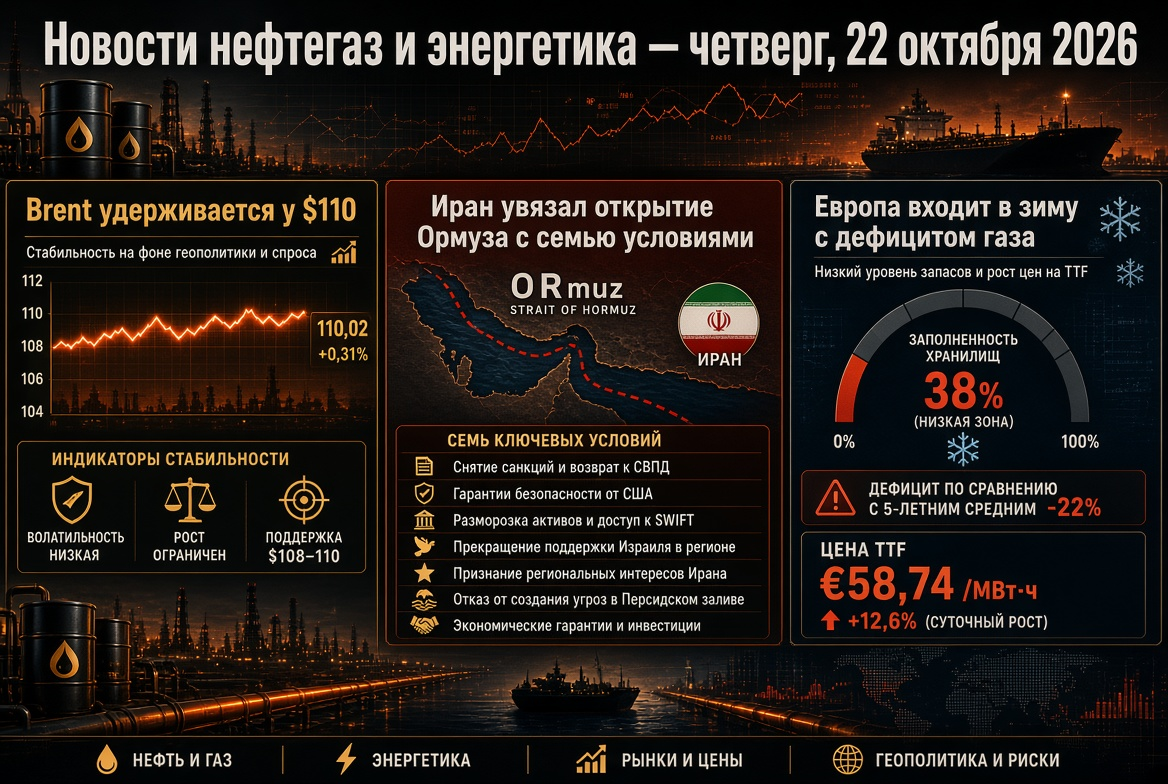
- Oil: Brent at around $110/barrel, WTI at around $99/barrel; since the beginning of the year, oil prices have increased by approximately 75%.
- Geopolitics: Tehran has stated that the Hormuz Strait will remain closed until Washington accepts Iranian terms.
- Gas: TTF at around €88/MWh, EU storage is approximately 74-75% full.
- Reserves: U.S. strategic oil reserves at their lowest since 1982.
- Coal: Newcastle at about $150/ton, reaching highs not seen in two years.
Oil Market: Brent Near Five-Month Highs
Oil prices experienced one of the most volatile days in October. On Tuesday, the December Brent contract was oscillating over $6: from $105.95 to $111.99 — a peak not seen since mid-May. The decline was triggered by rumors of an imminent deal between the U.S. and Iran, but by Wednesday, oil returned above $110 per barrel.
The market is supported by three factors:
- Declining Stockpiles in the U.S. Industry data from API recorded a decrease in oil, gasoline, and distillate stocks. A week earlier, the EIA reported a reduction in commercial crude oil stocks by 8.6 million barrels — down to 415.6 million, approximately 3% below the five-year average.
- Global Market Deficit. According to EIA estimates, global oil inventories decreased on average by 1.9 million barrels per day in Q3, with a continued decline expected in Q4.
- Risk Premium. Attacks on vessels in the Gulf of Oman are maintaining freight and insurance rates at high levels.
Hormuz Strait and the Tanker War: Diplomatic Stalemate
The crisis in the Hormuz Strait, which began on February 28, continues for over 230 days. Iranian Foreign Minister Abbas Araghchi confirmed that indirect contacts with the U.S. are ongoing through Pakistan and Qatar; however, the Strait will remain closed until Washington accepts Iranian conditions. U.S. Secretary of State Marco Rubio described reaching a deal as an extremely challenging task and emphasized that Iran's nuclear program remains a pivotal issue.
Analysts note the expanding geography of attacks: strikes on tankers are now extending beyond the strait to the Gulf of Oman, threatening the transshipment of oil between vessels. Meanwhile, oil exports from Gulf nations have partially recovered, while LNG supplies remain nearly paralyzed.
Saudi Arabia Under Attack from Houthis: Risks for Saudi Aramco
The second flashpoint of tension comes from Houthi attacks on Saudi oil infrastructure. On the night of October 14, a rocket strike hit the headquarters of Saudi Aramco in Dhahran: three upper floors of the administrative tower were damaged, with no casualties reported. The Houthis previously announced attacks on Aramco facilities in Riyadh and Yanbu. The group has promised to continue strikes on the kingdom's oil facilities, posing ongoing risks for the world's largest oil exporter and regional refineries.
OPEC+: Production Quotas on Hold, Focus on 2027 Base Levels
Seven key OPEC+ countries — Saudi Arabia, Russia, Iraq, Kuwait, Kazakhstan, Algeria, and Oman — have kept their production targets for November unchanged. The main quotas are as follows:
- Saudi Arabia — around 10.5 million barrels per day;
- Russia — around 9.9 million barrels per day;
- Iraq — around 4.4 million barrels per day.
The actual production of the group in August was about 25 million barrels per day — approximately 5 million below pre-war levels. The alliance's decisions have limited influence on the physical market: the main discussion shifts to auditing capacities and base production levels for 2027. Following the UAE's exit from OPEC in May, this process has gained additional significance. The next meeting is scheduled for November 1.
Strategic Reserves: U.S. SPR at Its Lowest Since 1982
U.S. strategic petroleum reserve levels have fallen to 283 million barrels — the lowest since October 1982 and about 40% of the design capacity. The U.S. Department of Energy has offered the market another 17 million barrels as part of coordinated IEA interventions. It is worth noting that in March, 32 agency countries agreed on a record release of 400 million barrels, and at the beginning of October, G7 countries agreed on an additional 100 million barrels of oil and diesel fuel.
For the market, this indicates that the "safety cushion" is depleting: subsequent replenishment of reserves will itself become a demand factor and support oil prices in 2027.
Gas and LNG: TTF at Four-Year Highs
The European gas market remains the main vulnerability point in the energy balance. The price at the TTF hub rose to €88.41/MWh — a nearly four-year high, with an increase of over 200% since the beginning of the year. Key drivers include:
- EU’s underground storage levels are around 74-75% full compared to a seasonal norm of 86-89%;
- Qatar's LNG exports in October may decrease to 0.6 million tons, with the force majeure from QatarEnergy extended until the end of November;
- Unplanned downtime at the Kårstø gas processing plant in Norway.
ING has raised its forecast for the average gas price this winter to €73/MWh. The median forecast from banks for Q4 is around €71/MWh, which is below market quotes and indicates a persistent risk premium.
Coal, Electricity, and Renewables
The gas shock has revived demand for coal. The Australian benchmark Newcastle is trading around $150 per ton — 45% higher than a year ago; on October 6, the price peaked at $152.20, the highest since October 2024.
In contrast, Europe’s electricity sector shows resilience thanks to renewable energy:
- The average electricity price in the day-ahead market in the EU decreased by 7% — from €103 to €91/MWh;
- Clean sources contributed about 73% of electricity generation in the EU;
- Solar generation increased by a record 36.4 TWh from January to August.
Renewable sources have effectively mitigated the transmission of the gas price shock to electricity prices, which supports the investment attractiveness of solar, wind projects, and energy storage systems.
Russia: Petroleum Products, Refineries, and Export Restrictions
The Russian market for petroleum products remains tightly regulated. The ban on gasoline exports is effective until January 31, 2027, while restrictions on diesel fuel exports for producers have been extended until the end of October amid postponed autumn refinery maintenance. Data on processing volumes and fuel sales on the exchange have been classified as restricted access information.
High oil prices and a softening of Washington's sanctions rhetoric have pushed Russian stocks to their highest since mid-June and support the ruble. Discounts on Russian oil for China have narrowed. Attention is focused on the Bank of Russia's meeting on October 23.
What to Watch for Investors: Calendar and Scenarios
- October 22: Market reaction to fresh EIA data on oil and petroleum product inventories, weekly statistics on gas inventories in the U.S.
- October 23: Decision by the Bank of Russia on the key interest rate.
- November 1: OPEC+ meeting on production policy for December.
- Early November: Midterm elections in the U.S., after which a revision of Washington's policy towards Iran may occur.
The baseline scenario for the oil and gas sector is the maintenance of Brent prices in the range of $105–115 per barrel until there is real progress regarding Hormuz. A U.S.-Iran deal could quickly alleviate the risk premium, while new strikes on Gulf infrastructure could push oil back to yearly highs above $120. For the gas market, key factors will be European weather and the timeline for restoring LNG supplies from Qatar.