Oil Market: Diplomacy Pressures Quotes, Geopolitics Maintains Premium
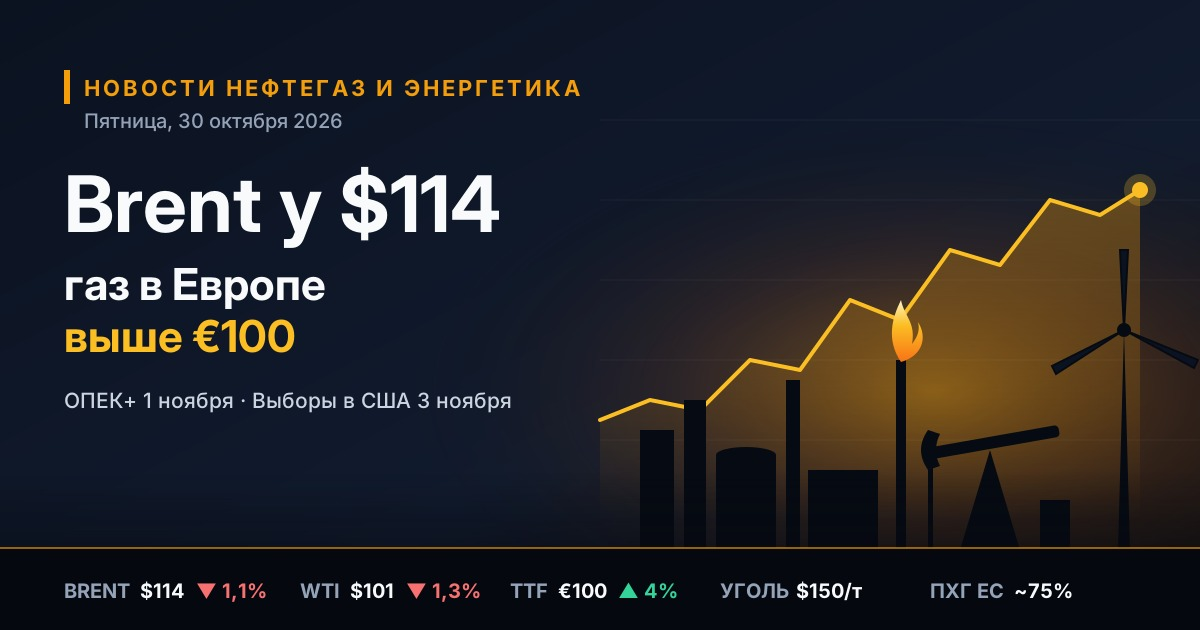
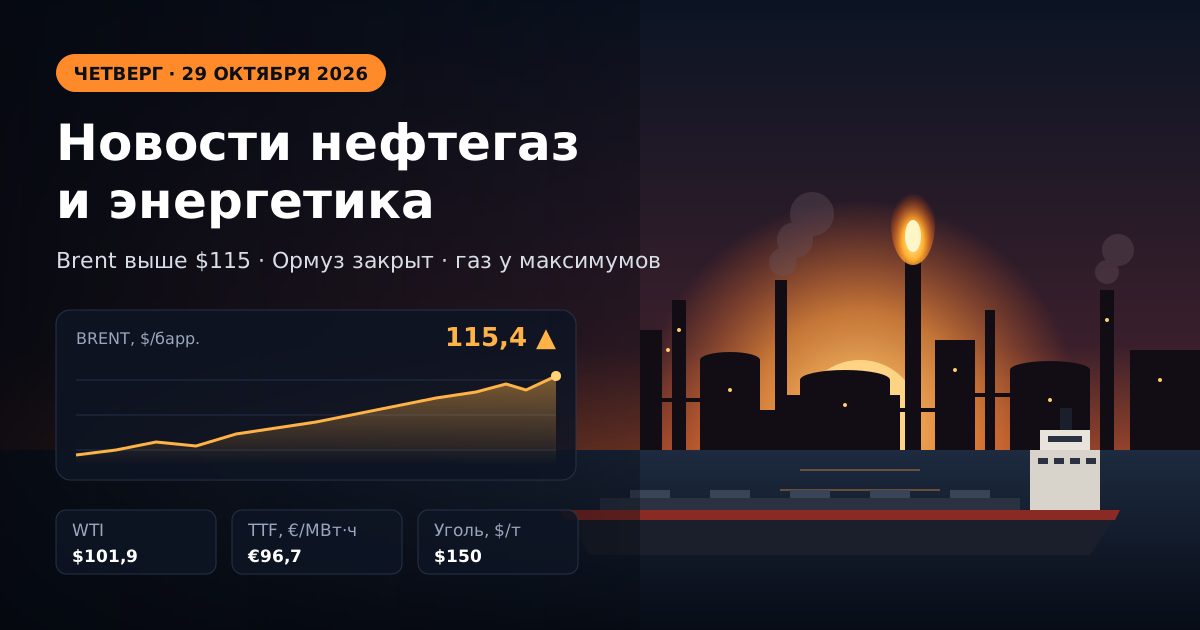
On Tuesday, January Brent futures slipped below $110 per barrel, while the nearby December contract traded around $114–116. This gap between contracts reflects deep backwardation: the market is paying a significant premium for immediate oil deliveries. WTI holds around $101, and the Brent–WTI spread has narrowed to about $9.
The key factors influencing oil price dynamics are:
- Diplomatic Track. Delegations from Saudi Arabia, Turkey, and Pakistan held discussions in Tehran early in the week, agreeing to continue contacts. This represents the first substantial argument for sellers since the military rally began.
- U.S. Political Calendar. Washington has previously indicated that it does not plan to strike Iran before the midterm elections on November 3, temporarily lowering the risk of sharp escalation.
- Monetary Policy. The Fed raised its rate in September for the first time in three years, and high oil prices are intensifying inflationary pressure and expectations of further tightening, which restrains demand for commodity assets.
- Technical Picture. Prices are stagnating at the upper boundary of the annual range; some analysts anticipate a correction, while in the event of new escalations, movement towards $120 by year-end is not ruled out.
Strait of Hormuz and Persian Gulf: Physical Risks to Oil Supply
Despite diplomatic signals, infrastructure risks remain unprecedented. Over the past week, Iran reported damage to seven tankers in a single night, while the IRGC announced the mining of an "unauthorized" southern route, where two supertankers with a combined load of over 4.5 million barrels were blown up. Yemeni Houthi forces continue attacks on Saudi Aramco facilities, prompting the company to evacuate personnel from its headquarters in the eastern province.
Nevertheless, oil exports from the Middle East have paradoxically rebounded: according to vessel tracking data, they surpassed 24 million barrels per day in the week ending October 18 — above pre-war levels. Saudi Aramco has more than tripled throughput through pipelines bypassing the strait to the Red Sea ports; however, the cost of insuring against military risks remains around 3% of the vessel's value.
OPEC+: Quotas on Paper and Meeting on November 1
The seven key participants of the alliance — Saudi Arabia, Russia, Iraq, Kuwait, Kazakhstan, Algeria, and Oman — have maintained target production levels for the second consecutive month. Riyadh's quota stands at 10.5 million barrels per day, while Russia's is 9.9 million. However, the group's actual production in August was about 25 million barrels per day, which is roughly 5 million below pre-war levels. The next meeting is scheduled for November 1; the market does not expect any changes to quotas until 2027, as the war has delayed the revisiting of production capacities for member countries. The discount of Russian Urals to Brent is estimated at $8–15 per barrel.
Gas Market: Europe Enters Winter with Lowest Stocks in 15 Years
November TTF futures rose to $1133 per thousand cubic meters on Monday — their highest since December 2022. On Tuesday, prices corrected to approximately $1100, while the December contract traded around €96 per MWh. This is nearly three times the average level of last winter.
The primary drivers of rising gas prices include:
- Shortage of LNG from the Persian Gulf. Supplies from the region, which accounted for about 20% of global liquefied gas supply, have fallen sharply; two Qatari liquefaction lines with a capacity of 12.8 million tons per year are out of commission for a period of three years.
- Low Storage Levels. EU storage facilities are approximately 74.9% full (around 80 billion cubic meters) — 14–15 percentage points below the five-year average. The European Commission has already lowered the target from 90% to 80% by December 1.
- Competition with Asia. European buyers are forced to pay a premium for spot LNG cargoes.
- Weather Factor. Cold weather has compelled several EU countries to start drawing gas earlier than usual.
Analysts predict prices could rise to $1200–1400 per thousand cubic meters in peak months during a cold winter.
Gas Exporting Countries Forum Summit in Moscow: Signals for the Global Gas Market
Vladimir Putin, speaking at the Gas Exporting Countries Forum summit, highlighted significant upheavals in the industry and linked the rising costs for European consumers to the rejection of Russian energy sources. Key points included:
- Global gas demand could rise to 5.5 trillion cubic meters per year by mid-century, with international trade reaching 1.7 trillion;
- To stabilize the market, conflicts must end and sanctions lifted;
- Producers prioritize stability over a twofold increase in spot prices;
- Russia is exploring the possibility of cooperating with American partners in the Arctic.
The Kremlin recently expressed readiness to discuss the resumption of gas supplies to Europe with interested buyers.
Oil Products and Refineries: Diesel Shortage and Regulation in Russia
The global oil products market remains significantly tighter than the crude oil market. Futures for fuel oil and diesel fuel in the U.S. are trading around $4.9 per gallon — more than double the level a year ago. The shortage of middle distillates supports refining margins and is beneficial for independent refineries with access to raw materials.
Russia has a complete ban on the export of gasoline, diesel, and marine fuel until January 31, 2027. Retail gasoline prices have risen by approximately 20.5% since the beginning of the year, while diesel prices have increased by 13.4%. According to mid-October data, the average gasoline price has decreased to 78 rubles per liter, yet the situation remains fragile: refineries are operating at maximum capacity, scheduled repairs have been postponed, and data on refining are classified.
Electricity and Renewables: Energy Crisis Accelerates Energy Transition
High fossil fuel prices enhance the economic arguments for renewable energy. By spring 2026, wind and solar generation is expected to surpass gas generation globally for the first time in history, providing 22% of electricity production compared to 20% from gas. In the U.S., a record 86 GW of new capacity is anticipated to be added this year, over 90% of which will come from solar stations, storage, and wind. Indonesia, South Korea, and several other countries are fast-tracking renewable energy development programs, viewing them as tools for energy security and reducing dependence on LNG imports.
Coal: Asian Demand Supports Prices
High gas prices are prompting a shift in some energy systems in Northeast Asia towards coal. Prices for thermal coal at the Australian Newcastle hub reached three-year highs in October, with the average price forecast for 2026 at around $130 per ton FOB. However, the growth of renewables is limiting imports: forecasts for coal purchases by China, India, and Japan for the current year have been downgraded.
What Matters to Investors: Key Indicators for the Week
- Negotiations on Iran — the main factor for oil and LNG; progress could remove some geopolitical premium.
- Weekly U.S. Oil Inventory Data — an indication of supply-demand balance.
- ECB Decision — impact on the euro and the dollar-denominated gas prices.
- OPEC+ Meeting on November 1 — the baseline scenario expects quotas to remain unchanged.
- U.S. Elections on November 3 — risk of changes in Washington's foreign policy direction.
- Weather and Gas Draw from UGS in Europe — an indicator of winter gas and electricity prices.
The oil and gas market remains in a state of high volatility, where diplomatic news and incidents in the Persian Gulf can change prices by several percent in a single session. For oil, gas, and fuel companies, as well as investors in the commodity sector, the coming two weeks will test the resilience of current price levels ahead of the heating season.