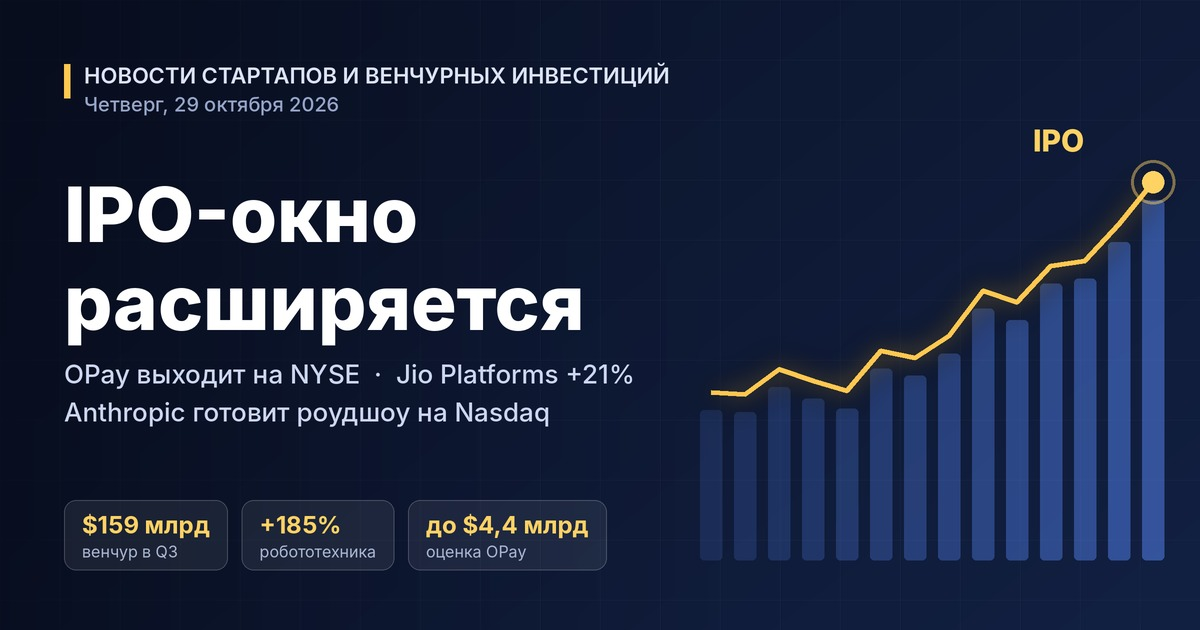
Key themes of the day for venture investors and funds:
- IPO market — OPay on the NYSE, Jio Platforms' debut, Anthropic's preparations for a Nasdaq listing.
- AI mega-rounds — deals worth hundreds of millions and billions of dollars at valuations above $5bn.
- Physical AI and robotics — the sector with the fastest funding growth in 2026.
- New venture funds — from multi-billion-dollar pools to niche first-time funds.
- M&A and exits — strategic purchases of technology and teams.
Macro picture: the venture market after a record half-year
According to Crunchbase, global venture investment in the third quarter of 2026 amounted to about $159bn. That is 25% below the record $212bn of the second quarter, but 53% above the figure a year earlier. About two-thirds of the capital went to companies connected with artificial intelligence.
The quarterly decline should not be interpreted as a reversal of the trend: the second quarter was inflated by isolated ultra-large deals. The structure of the market remains intact:
- Capital is concentrated in the segment leaders — a small number of rounds accounts for the bulk of the volume.
- Investors are shifting from "pure" AI models to companies that turn AI into operating results.
- The role of late stages and secondary deals is growing as the exit window opens.
Anthropic: prospectus published, market awaits the price range
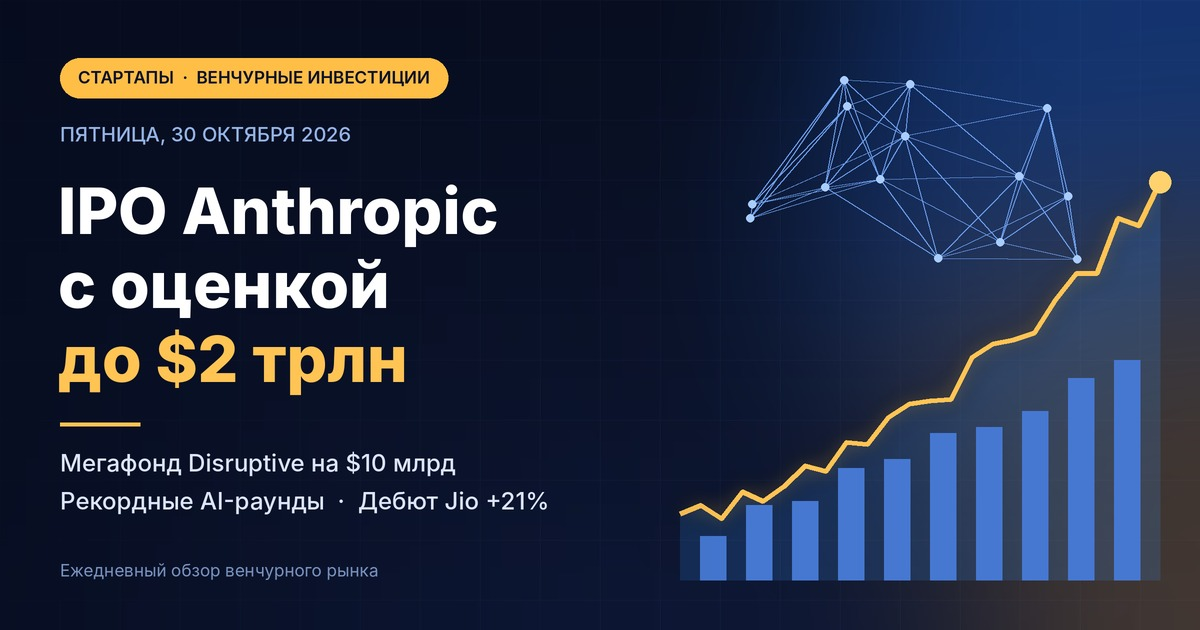
The main event of the week remains the public S-1 filing of Anthropic, submitted on 26 October. The developer of Claude plans to list Class A shares on the Nasdaq Global Select Market under the ticker ANT. Revenue for the first half of 2026 was about $16.3bn against $1.2bn a year earlier; in the second quarter the company reached operating profit.
What matters for investors:
- The price range and offering size have not yet been disclosed — they will be shown in an amendment to the S-1.
- According to the US press, trading could begin in the week of 16 November.
- Market participants estimate the potential proceeds at around $75bn — comparable to SpaceX's IPO.
- Commitments to purchase computing capacity exceed $400bn over a horizon of up to 20 years.
- A non-standard lock-up schedule allows insiders to sell shares from the first day of trading.
For venture funds, the Anthropic listing will be the largest potential exit of the decade, and for the entire industry — a valuation benchmark for AI labs.
IPO market: OPay, Jio Platforms and biotech offerings
On Wednesday, 28 October, Jio Platforms held the largest IPO in India's history: the company raised about ₹30.2 thousand crore, and the shares opened at a premium of about 21% to the offer price. The order book was oversubscribed more than 20 times, while qualified institutional investors submitted bids for an amount 70 times the offer.
On Thursday, 29 October, the debut of OPay on the NYSE is expected:
- Range — $19–21 per depositary share, about 16m securities.
- Target valuation — up to $4.4bn against $2bn in the 2021 round led by SoftBank.
- Revenue for the first half of 2026 grew 137% to $467m, net profit — to $91m.
- Standard Bank is investing up to $200m through a parallel private placement.
The offering will be the first US IPO of a fintech serving predominantly Nigerian clients, and will set a valuation benchmark for the entire African venture sector. In the same week, biotech companies Aspen Neuroscience and Bambusa Therapeutics are preparing for Nasdaq listings with a range of $15–17 per share.
Mega-rounds in artificial intelligence
October has become one of the busiest months of the year by volume of large funding rounds. The most notable deals of the past two weeks:
- Ramp — $1.85bn at a $60bn valuation; the corporate spend management fintech is building its strategy around AI agents.
- Tenstorrent — $1.5bn in a Series E round at a $6.2bn valuation to develop an open architecture for AI chips.
- Flapping Airplanes — $1bn in Series A at a $6bn valuation led by Index Ventures and Lux Capital, without a commercial product or revenue.
- Legora — $550m at an $8.8bn valuation; the Swedish legal-tech confirms its status as a European leader.
- Pigment — $250m at a $2.3bn valuation with planned participation from Nvidia.
- Whop — $200m in Series D at a $5.1bn valuation.
The infrastructure layer stands out separately: General Compute raised $100m in Series A, Hyperbolic — $30m to aggregate capacity from independent cloud providers, and Daytona joined the "unicorn" club with a $1bn valuation.
Physical AI and robotics: the fastest-growing segment
According to Crunchbase, funding for robotics startups in the third quarter grew 185% year on year, with the US and China remaining the leaders. Recent deals confirm the trend:
- Bedrock Robotics — $600m in Series C for autonomous excavators; cumulative funding has approached $1bn.
- Warhound — $200m at a $1.2bn valuation with participation from Sequoia, 8VC and In-Q-Tel.
- Machenta — $40m in seed funding for training robots in simulation.
For funds this is a signal: the cost of entry into robotics at early stages is rising fast, and defence and industrial applications are becoming a separate investment thesis.
Fintech, climate and vertical AI
Diversification of the venture portfolio continues. Among the notable deals of the week:
- Nevis — $70m in Series B led by EQT Ventures for an AI-powered wealth management platform.
- Peak Energy — $108m in Series B for sodium-ion energy storage systems.
- Town — $108m in Series B for an AI assistant for team collaboration.
- Emvolon — $22m in Series A for modular units converting methane into biomethanol.
Venture funds: large capital and specialisation
Fundraising by management companies remains active, with LPs favouring well-known brands and narrow specialisation:
- Disruptive is forming a fund of up to $10bn with a concentrated bet on a limited circle of companies.
- Spectrum Equity closed the largest growth fund in its history at $2.5bn.
- Seaya held the first close of its new Nova growth fund at €600m.
- Inspired Capital raised $450m for its fourth fund with a focus on New York.
- Trust Ventures filed documents for a $400m Fund V, while Benchmark registered partner funds with the participation of Jack Altman.
At the same time, the median new venture fund remains small — about $3.4m, reflecting the polarisation between mega-funds and micro-funds.
M&A and strategic deals
Consolidation is concentrated in AI infrastructure and semiconductors:
- Anthropic disclosed the acquisition of Mithril Medicine — a one-employee biotech startup that used Claude to develop a drug candidate for a rare form of muscular dystrophy.
- Unconventional AI is acquiring Israeli processor developer NeuReality.
- SG Micro is buying a controlling stake in Shenxiling Microelectronics for about $114.5m.
Central Asia, Russia and the CIS
Regional startup ecosystems are showing moderate but steady activity. Kazakh AI startup Riasm raised $3m in a pre-seed round, Jooba — $4m in seed investment, while Astana Hub continues to act as a point of attraction for international capital. A Moscow venture fund will allocate RUB 250m to technology companies with a target co-investment volume of about RUB 1bn. Additional interest in the region is created by inDrive's plans to test robotaxis in Central Asia in 2027 together with Pony AI and Nvidia.
Conclusions for investors
The venture market at the end of October 2026 is defined by three factors: the opening IPO window, the concentration of capital in AI leaders and the rapid growth of physical AI. In the coming weeks, investors should monitor:
- Anthropic's price range and demand in the order book;
- the performance of OPay and Jio Platforms shares after debut as an indicator of appetite for emerging markets;
- the resilience of valuations in AI mega-rounds amid public market volatility;
- the pace of venture fund fundraising ahead of 2027.
Successful offerings could launch a cycle of LP capital returns and a new wave of venture investment in startups, however valuation discipline remains the key condition for quality growth of the market.