Key Startup and Venture Investment News for October 15, 2026: Third Quarter Results, Anthropic IPO Preparation, Mega-Rounds in AI, Quantum Technologies, and Defense, Major M&A Deals, and New Venture Funds
The global venture market enters mid-October 2026 with mixed signals. Venture investment volume over the first nine months has reached a historic high. However, capital is becoming increasingly concentrated among a narrow circle of companies linked to artificial intelligence. For venture investors and funds, three themes stand out: the preparation for the largest IPO of the decade, a record number of rounds exceeding $1 billion, and a resurgence of M&A deals as an exit channel.
Key events shaping the startup market agenda this week:
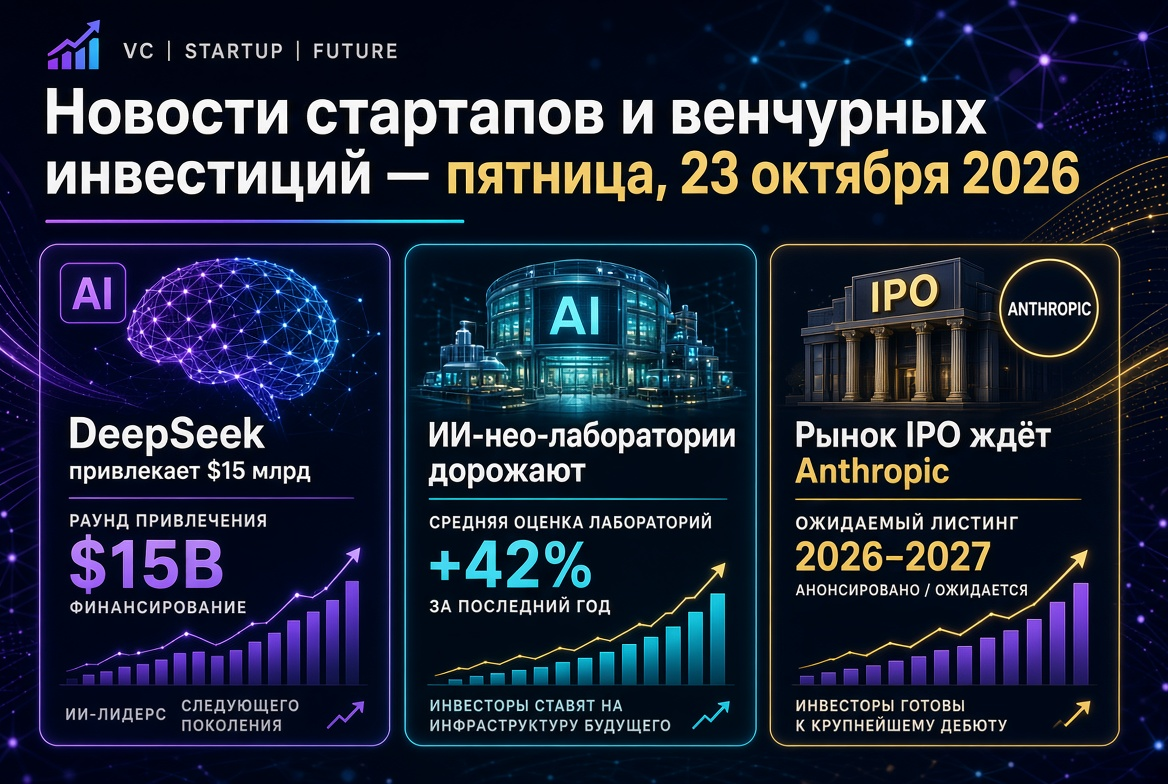
- Anthropic IPO pushed to November — roadshow expected to start the week of November 9, with target valuation discussed around $2 trillion.
- Record mega-rounds — in the third quarter, 27 startups raised rounds of $1 billion and above.
- Chinese AI accelerates — DeepSeek, Manus, and Infinigence AI have closed major funding rounds.
- M&A at the intersection of quantum technologies and cybersecurity — IonQ acquires Elisity for up to $1.3 billion.
- Record fundraising in the UK — British venture funds raised $6.9 billion in the quarter.
Third Quarter Results: Record Nine Months and Rising Capital Concentration
According to Crunchbase, the global venture capital volume in the third quarter of 2026 amounted to $159 billion, with nearly 6,000 funded startups. This is a 25% decline from the record second quarter ($212 billion) but a 53% increase year-on-year. Over nine months, the venture market attracted $679 billion, the highest figure for the same period in history.
Key parameters for the quarter:
- $102 billion, or 64% of all venture investments, went to AI startups.
- 27 rounds of $1 billion+ — an absolute record compared to 16 in the second quarter and 14 in the first; they accounted for nearly a third of all capital.
- $91 billion (57%) was raised by American companies, with about a quarter of the global volume coming from the San Francisco Bay area.
- Early-stage funding grew by 25% year-over-year — to $40.6 billion, indicating sustained appetite for seed and Series A rounds.
Data from PitchBook and NVCA for the U.S. confirms the trend: from January to September, the volume of venture deals in the country reached $515.8 billion, with 82.7% attributed to AI. However, first-time fund managers have closed only 81 funds totaling $4.9 billion, demonstrating ongoing challenges for new teams in competing with mega-funds.
Anthropic IPO: November Window and Valuation Debate
The major topic for the public market is the preparation for Anthropic's IPO on Nasdaq. According to recent reports, the roadshow has been postponed by about a month and may start the week of November 9, allowing for a debut before Thanksgiving. The company is expected to disclose its third-quarter financials ahead of marketing the offering.
- Last private valuation — about $965 billion following the Series H round in May 2026.
- IPO benchmark — investors are discussing a valuation in the range of $1.8–2 trillion, aiming to raise up to $100 billion.
- Skeptics — independent analytics firm New Constructs has labeled the upcoming offering as overvalued and has appraised the business significantly lower than market expectations.
For venture investors, the risk factor is clear: shares of SpaceX, which went public in the summer with a valuation of around $1.77 trillion, lost about half their value by the end of July. The outcome of Anthropic's IPO will serve as a key indicator of whether the public market is willing to pay private market multiples for AI companies.
AI Mega-Rounds: Models, Defense, and Legal Technologies
October continues the series of major funding rounds in the artificial intelligence segment. The most notable deals include:
- Shield AI — $1.5 billion in Series G at a valuation of $12.7 billion; defense autonomous systems have firmly entered the mainstream of venture investments.
- Legora — $550 million in Series D at a valuation of $5.55 billion; legal AI remains one of the strongest verticals of the year.
- Temporal — $550 million in Series E for developing workflow orchestration infrastructure.
- Arena — $200 million in Series B at a valuation of $3.1 billion led by Lightspeed and Khosla Ventures; demand for AI agent evaluation and testing is rising.
- Applied Intuition — reportedly receiving investor offers at a valuation of around $30 billion.
An important signal: "lab" valuations are now being achieved not only by fundamental model developers but also by applied AI startups selling solutions for specific industries.
China: DeepSeek, Manus, and the Bet on Domestic AI Infrastructure
The Chinese venture segment is showing notable rejuvenation:
- DeepSeek closed its first external round — over $12 billion at a valuation exceeding $50 billion with participation from Tencent and CATL, and subsequently led the seed round of robotics startup Winverse AI with a valuation of around $400 million.
- Manus raised over $500 million led by Boyu Capital and IDG Capital — the first round after Beijing blocked its acquisition by Meta.
- Infinigence AI secured 2.3 billion yuan (approximately $344 million) in Series C for developing AI infrastructure.
- Fujian Fulian Integrated Circuit raised nearly 1 billion yuan in a strategic round supported by governmental industry funds.
Deep Technologies: Quantum Computing, Neurointerfaces, and Chemistry
Venture capital is increasingly funding deep tech projects with long payback horizons:
- Oratomic — $475 million in Series B for creating fault-tolerant quantum computers.
- Sabi — $50 million seed round led by Khosla Ventures for a brain-AI wearable interface.
- Albert — $55 million in Series B led by TCV for an AI platform for chemical research.
- Soufflé Therapeutics — oversubscribed Series B round of $135 million for advancing clinical programs; biotech is regaining investor trust.
M&A Deals: IonQ Acquires Elisity
The largest deal of the week in the mergers and acquisitions market was IonQ's agreement to acquire Elisity — a developer of Zero Trust solutions — for up to $1.3 billion in stock, including up to $150 million in performance-based payments. Closure is expected in the fourth quarter.
- This is already IonQ's third major purchase following SkyWater Technology ($1.8 billion) and Oxford Ionics ($1.1 billion).
- The rationale for the deal is to combine post-quantum cryptography with access control for users, devices, and AI agents.
- The market reacted cautiously: IonQ shares fell amidst fears of capital dilution.
For funds, this deal shows that strategic buyers are willing to pay a premium for cybersecurity startups with growing revenues and a corporate customer base.
Europe: Record Fundraising in the UK and Energy Unicorns
According to HSBC Innovation Banking and Dealroom, British venture funds raised a record $6.9 billion in the third quarter across 31 funds — more than four times the average quarterly level of the past two years. British startups attracted $6.1 billion, and over nine months — $23.3 billion, or 35% of all venture investments in Europe.
Among notable European deals:
- 1KOMMA5° (Germany) — €70 million at a valuation of $1.35 billion, the company is preparing for a U.S. launch and considering an IPO.
- Epyr — €15 million for industrial heat electrification.
- Ambio (Finland) and OlsAro (Sweden) — seed rounds of around €5 million in the plastic recycling and agri-tech sectors.
New Venture Funds and Capital Market for LPs
In the context of capital concentration in mega-funds, early-stage managers continue to close new funds:
- Pear VC raised $333 million for its fifth fund focusing on the earliest stages.
- DataTribe has begun raising its fourth fund in cybersecurity.
- Monte Carlo Capital completed the first close of its second fund at €13 million with a target volume of €26 million.
In India, startups raised $2.9 billion in the third quarter, led by electric mobility and AI. In Russia, the number of Skolkovo residents exceeded 5.4 thousand, with investments in them reaching a record 43.7 billion rubles.
What This Means for Venture Investors
The venture market in October 2026 remains record-high in volume, but increasingly selective in access to capital. Key takeaways for funds:
- Concentration is the main portfolio risk. A third of quarterly capital went to 27 companies, while the average startup competes for a shrinking market share.
- Anthropic's IPO will set the tone for exits. A successful offering will open a window for other late-stage AI companies, while an unsuccessful one will hit valuations in the secondary market.
- M&A is becoming a full-fledged exit channel, especially in cybersecurity, quantum technologies, and infrastructure.
- Early stages remain an entry point — a 25% year-over-year increase in funding gives seed and Series A funds space for deals at reasonable valuations.
In summary: startups and venture investments are entering the final quarter of the year at peak activity but with a growing divergence between AI leaders and the rest of the market. Upcoming weeks — Anthropic's earnings release, the TechCrunch Disrupt conference in San Francisco, and the closing of major M&A deals — will determine investor sentiments leading up to the end of 2026.