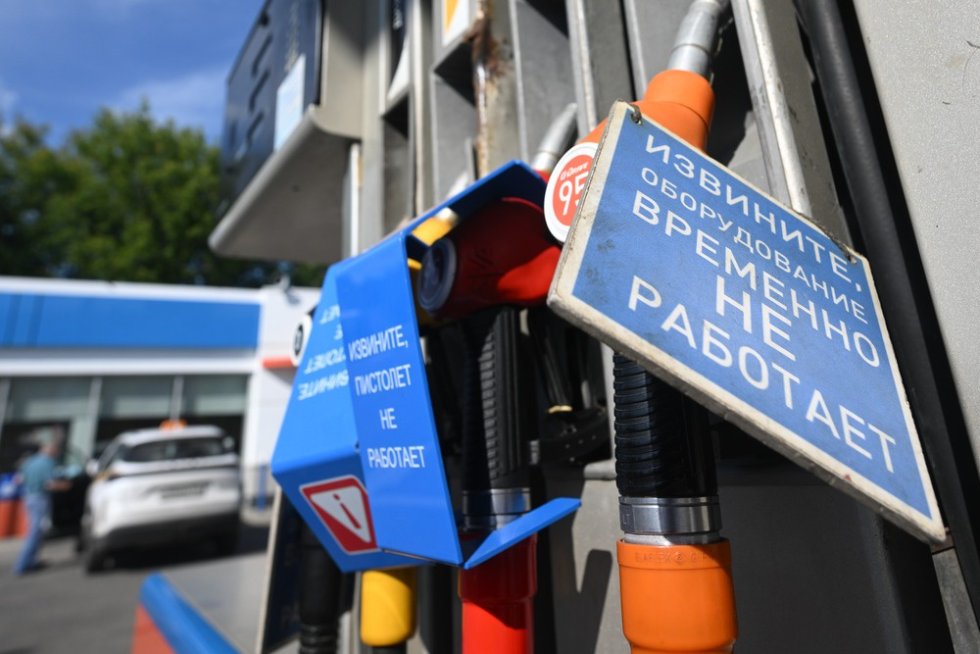
The number of fuel stations (FS) for sale in Russia is increasing. This trend applies not only to individual independent FSs that are not owned by major oil companies but also to networks that are "dumping ballast" by shedding their least profitable assets.
The number of listings for the sale of FSs on various trading platforms and oil company websites has increased 5.5 times over the last five years. However, a listing does not necessarily indicate that a sale will occur. Rather, it is an indicator that owners want to divest from their businesses.There are typically two reasons for such a move: the desire to profit from selling a promising business or, conversely, an attempt to rid oneself of a loss-making enterprise. In the latter case, if the asset cannot be sold, it is highly likely that it will be closed down. This, in turn, affects fuel supply, especially in regions where there are no large network FSs. Additionally, a reduction in the number of players inevitably leads to decreased competition, resulting in either price increases or maintained high prices.
FSs for sale include not only single stations but also entire regional networks.The number of FSs in Russia began to decline in 2025, according to "OMT-Consult," by 1.6%. This downward trend continued in the first half of this year, with a further drop of 1%. Significantly, mobile FSs (container stations) have largely disappeared.
By the second half of 2026, there were approximately 28,000 fuel stations in Russia, with just over 23,400 being conventional FSs (non-mobile stations selling gasoline and diesel).
The share of independent players in the total number of stations is around 65%. They are most concentrated in the east and south of Russia. However, in terms of gasoline and diesel sales volumes, independents account for only 30% of the market. Primarily, independent FSs purchase fuel for their stations in small wholesale, a segment that saw the highest price hikes this summer with supply disruptions. Hence, there may be a desire among owners to sell their businesses, although this process also affects larger players.
For instance, last week, operating FSs, land plots for business along federal highways, as well as production sites of "Bashneft-Retail" were listed for sale or rent. The number of objects can be inferred from their geography, covering Sverdlovsk, Chelyabinsk, Kurgan, Orenburg, Samara, Ulyanovsk, Penza, Vladimir, Moscow, Ryazan, and Smolensk regions, as well as the Republics of Tatarstan, Mordovia, Udmurtia, Chuvashia, and Mari El. Earlier, it was reported that "Gazprom" and "Lukoil" were selling their "non-core" FSs. Lukoil's website still lists eight FSs for sale.
Regarding independent players, everyone is aware of the issues facing one of the largest independent FS networks, "Trassa," which is grappling with a debt crisis and may face external management or go under the hammer. Currently, around 170 FSs are for sale on various trading platforms.
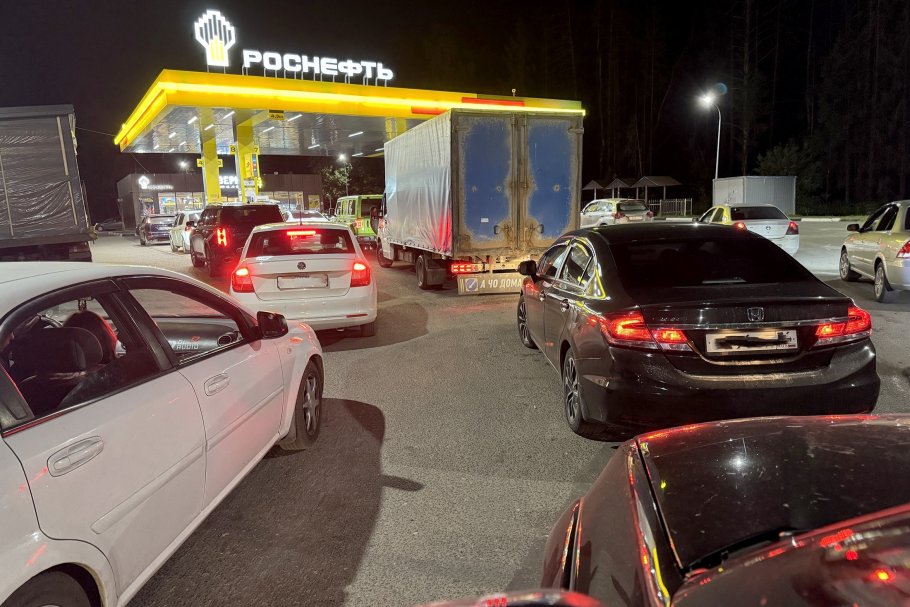
However, as noted in a conversation with "RG" by Yuri Stankevich, Deputy Chair of the State Duma Energy Committee, it is not entirely appropriate to speak of a "mass sell-off." Today, fuel retail presents a heterogeneous competitive landscape, with segments in different regions of the country varying significantly. The fuel shortage has primarily affected independent FSs, where such stations have often "sucked off the hoses," contributing to the perception of market saturation, with assets that are de facto underutilized.
Yet, the geography of FS sale listings spans almost the entire country. According to Sergey Tereshkin, CEO of Open Oil Market, the root causes are the decreasing profitability of FS operations and issues with fuel availability for trade. Exchange prices for gasoline and diesel have risen by 30-37%, even higher in the small wholesale segment, resulting in fuel retail being in a tougher situation compared to the oil refining segment, which is subsidized.
Additionally, fuel availability on the exchange has been affected by reduced mandatory sales quotas for major oil companies. The lower the quota and the more significant the relaxation of non-exchange transactions, the smaller the volume of fuel available for traders. Ultimately, independent FSs suffer losses, purchasing gasoline and diesel from traders. A reduction in physical sales volume means that FS operators earn less from each liter of fuel sold.
According to Sergey Frolov, managing partner at NEFT Research, the redistribution of ownership in the retail fuel market under current conditions was expected. Currently, private owners of single FSs or small networks with low efficiency are exiting the business. Major oil companies are also optimizing unprofitable points and restructuring their networks to adapt to new conditions.
The expert believes that a decrease in the number of FSs is unlikely to have a significant impact on the overall situation in the fuel sector, as they were often left empty anyway. With improvements in fuel supply conditions, the number of private FSs is likely to rise again, especially if high prices persist.
It is hardly possible to sell a FS now; this should have been done two years ago when this business was profitable, states Dmitry Gusev, Deputy Chair of the Supervisory Board of the "Reliable Partner" association and member of the expert council for the "FS of Russia" competition. However, the issue is not about trying to sell them but rather that we do not know how much we actually need these stations. Meanwhile, priorities for the domestic fuel market have been defined. The main task is to secure supply for large companies' network stations, agricultural producers, and industrial enterprises, but not independent FS networks, the expert clarifies.
A similar opinion is shared by Stankevich. "Unfortunately, the situation in 2026 demonstrated that the retail fuel market has developed chaotically over the years. We do not have a qualified understanding of the adequate number of FSs, the existence of which allows us to confidently speak about the availability of infrastructure for consumers. Systematic planning of retail network development is not being carried out, resulting in many municipalities, even in Central Russia, lacking properly functioning stations on their territory. For instance, systematic planning similar to that for electricity and heat supply facilities is conducted at the level of documents that are regularly updated by the government (location schemes for facilities). The situation in fuel retail also needs to be fixed," he said.
Source: RG.RU