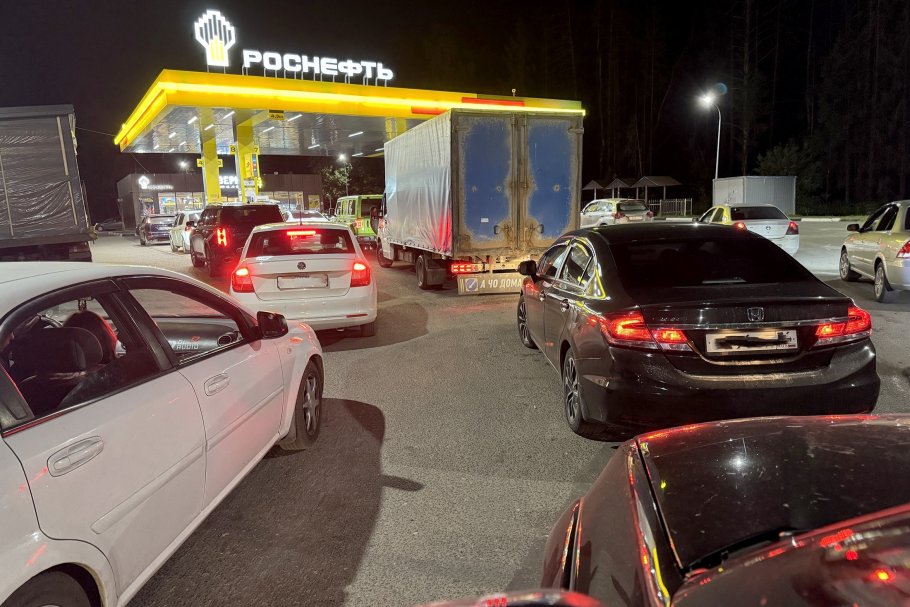
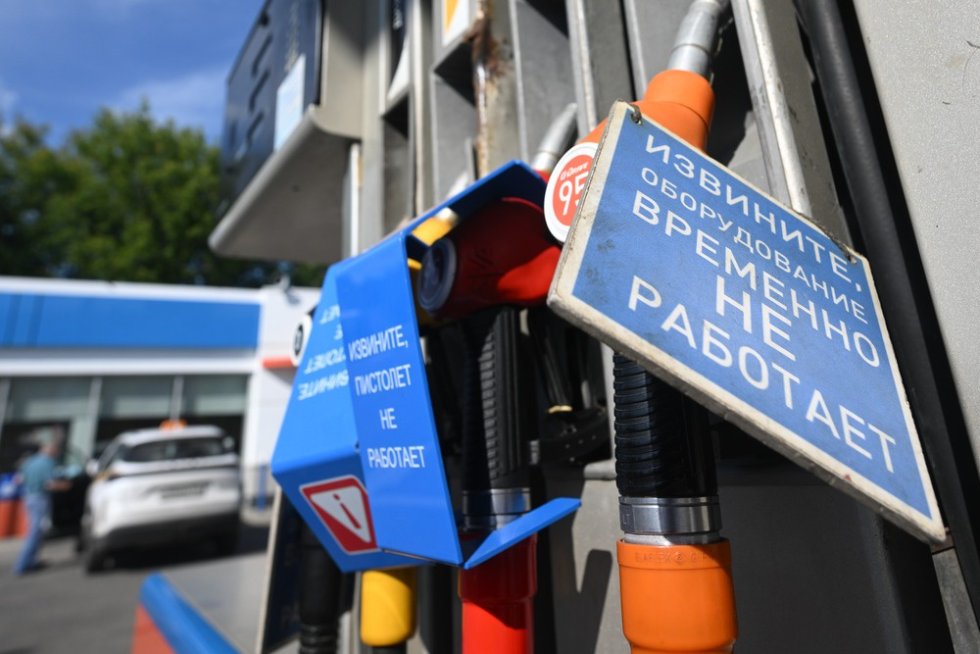
In August alone, sea deliveries of petroleum products to Russia from abroad exceeded 300 thousand tons. It is highly likely that the entire volume or the overwhelming majority was gasoline, which was in short supply at filling stations (petrol stations), prompting long queues. Approximately 160 thousand tons were delivered to Murmansk, while the remainder went to the Baltic ports. Supplies originated from India, Morocco, and Turkey. Additionally, there were media reports of Egyptian fuel being delivered to Arkhangelsk and gasoline from South Korea to Vladivostok.
The primary issue with imported gasoline in Russia is its price. All the mentioned exporting countries are also importers of crude oil. It cannot even be ruled out that the gasoline they sent us was produced from Russian oil. As explained in an interview with "RG" by Victoria Trifonova, senior analyst at the analytical center "Yakob and Partners," imported fuel includes not only the cost of gasoline itself but also shipping, insurance, transshipment, and subsequent transportation within Russia. An additional factor is the infrastructural limitations in receiving, transshipping, and blending petroleum products at Russian ports. For the supplier, selling such gasoline on the exchange means either setting a significantly higher price or selling with insufficient margins.
Indeed, in August, when gasoline from abroad was traded on the exchange, it was sold at a price of 105 thousand rubles per ton, which was 39% higher than the then-current exchange quotations for AI-92 (75,530 rubles per ton). Currently, the quotations stand at 69,819 rubles per ton, while imported gasoline has hardly become cheaper.
However, the absence of exchange transactions now and the fact that only slightly over a thousand tons were traded in August does not imply that Indian or Moroccan gasoline is not being sold. For example, in August, Russia imported 188 thousand tons of Belarusian gasoline (deliveries occur via rail and road), of which only 26 thousand tons were traded through the exchange.
Most of the imported marine fuel is sold through direct contracts, bypassing the exchange, according to Sergey Frolov, managing partner at NEFT Research. Direct supplies are significantly increasing: while in August, the "First Murmansk Terminal" shipped around 10 thousand tons of fuel (directly) to the domestic market, by early September, this figure had already exceeded 20.4 thousand tons. This means that fuel is being distributed to filling stations— including large oil companies—directly, without public trading, he emphasizes.
If imported gasoline is not available on the exchange, it does not mean it is unavailable in Russia, confirms Dmitry Gusev, deputy chairman of the Supervisory Board of the "Reliable Partner" Association and member of the Expert Council for the "Gas Stations of Russia" competition. The role of exchange trading in Russia has significantly diminished, with mandatory sale quotas for gasoline through the exchange for large oil companies reduced from 15% to 10%, prioritizing direct contracts between suppliers and buyers. The exchange has now become more of a pricing benchmark, reflecting neither the actual market state nor playing a significant role in price formation.
This situation has its drawbacks. As Trifonova notes, the more fuel is distributed through direct contracts, the lesser the role of the exchange as a public price indicator, making it increasingly difficult for independent filling stations (which constitute over half of the gas stations in Russia) that do not belong to large oil companies to access fuel supplies. This is particularly challenging for smaller chains lacking developed logistics. For the market, a balance is essential: the ability to swiftly reallocate scarce resources through direct contracts on one hand and maintaining adequate transparency and competition on the other, the expert believes.
Meanwhile, the government is discussing measures to enhance the appeal of imported fuel for our market. A damper mechanism has already been implemented for these supplies—this is a subsidy from the budget that compensates importers for part of the difference between the indicative wholesale prices (set by the state for a year) in Russia and the cost of fuel in external markets. Delivery costs are also considered, but only up to the Russian port.
The main supplier of gasoline to Russia from abroad is Belarus.Recently, Deputy Finance Minister Alexey Sazanov stated that the Ministry of Finance is prepared to consider the proposal from the Ministry of Energy to include transportation costs from Russian ports to consumption regions in the damper calculation.
Trifonova believes that accounting for transportation costs for imported fuel within Russia could significantly improve the economics of such supplies. However, this measure will not bring imported fuel back to the exchange.
Frolov clarifies that discussions are also underway regarding the extension of the zero import duty on gasoline until mid-2027 (currently set to expire at the end of 2026). However, the Ministry of Finance does not currently support recognizing the foreign premium (the difference between the purchase price and the exchange benchmark), arguing that its size cannot reliably be determined. Thus, the approach is: compensate for logistics within the country—yes, compensate for the purchase price abroad—no, the expert emphasizes.
There remains a question of how critical marine supplies of imported fuel are for us at present. According to Sergey Tereshkin, General Director of Open Oil Market, it can be confidently stated that supplies from India or Turkey are not yet playing a significant role. This is their key difference from supplies from Belarus. The share of Belarusian supplies in gasoline consumption in Russia has increased from 2% to 6%. In some regions, it can be even higher. Building the infrastructure for supplies from abroad is a challenging task, particularly now that global oil refining is at multi-year lows, and the underutilization of Middle Eastern refineries has already become one of the reasons for the shortage in the global fuel market.
Source: RG.RU