Oil Market: Weekly Gains Amid Continued Risk Premium
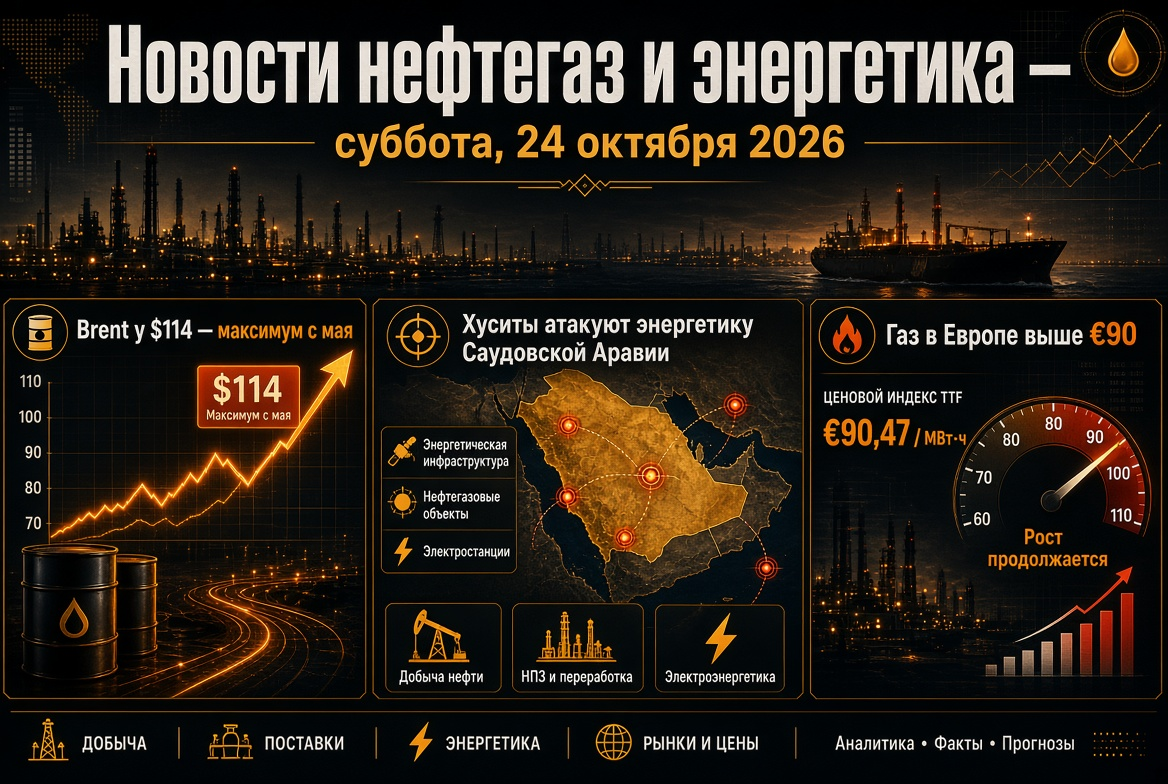
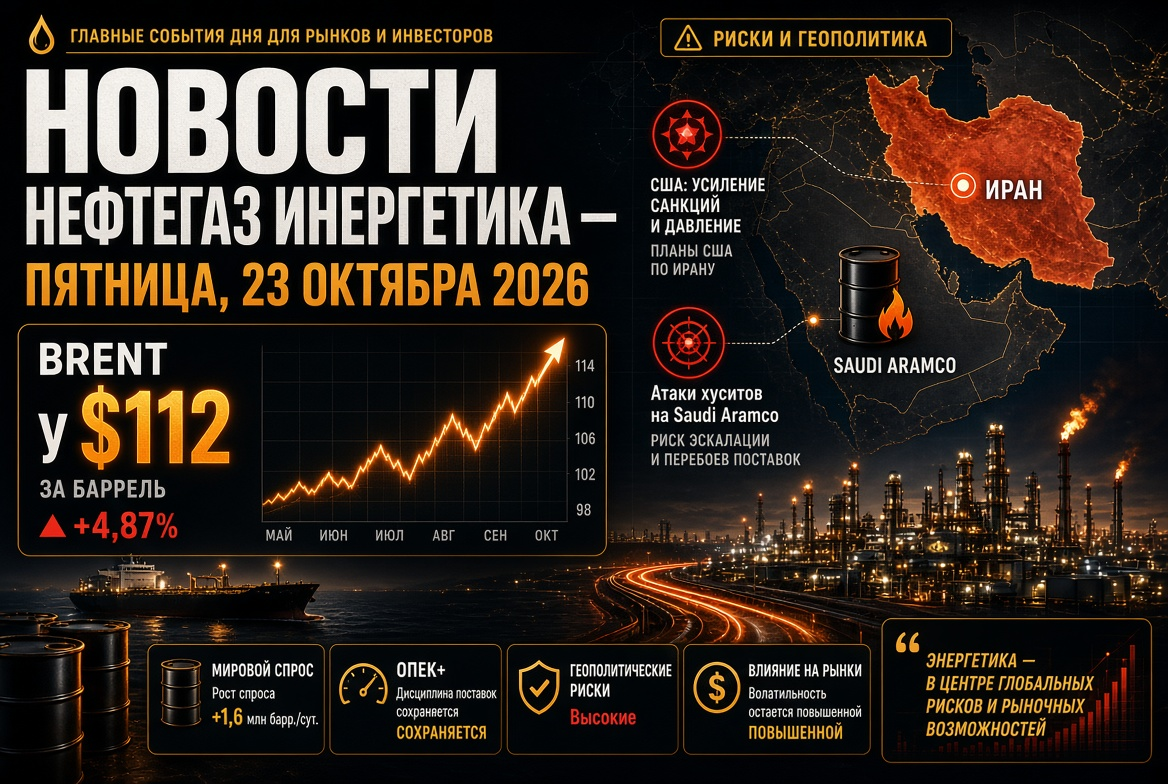
On Friday, oil prices saw a moderate decline; however, the week ends positively for the oil market. December futures for Brent traded in the range of $105–105.5 per barrel, while WTI hovered around $97.
- Weekly dynamics: Brent gained less than 1%, while WTI increased by around 6%.
- U.S. inventories: Commercial oil inventories fell by 8.5 million barrels in the week ending October 9, contrary to expectations of a slight increase. This marks the largest drop since the onset of the war.
- Hurricane factor: Some production in the Gulf of Mexico was temporarily halted, supporting the U.S. grade.
- Brent-WTI spread: The spread narrowed to about $8 per barrel after exceeding $9 at the beginning of the week.
Brent remains approximately 70% more expensive than a year ago. Analysts note that the market maintains a significant geopolitical premium, which could only be alleviated through an agreement between the U.S. and Iran.
Strait of Hormuz: Oil Flows Recovering, But Unsteadily
The situation in the Strait of Hormuz remains a key pricing factor for oil, LNG, and petroleum products.
- Raw material flows. In the week leading up to October 13, an average of about 11.6 million barrels per day passed through the strait—approximately 68% of the pre-war level of 17.15 million.
- Shipping. The number of transits in the week decreased to 131. Many container lines have rerouted their paths to bypass the strait.
- Incidents. Following the sinking of the container ship GFS Pride, new reports have emerged of a fire on a tanker in the Gulf of Oman.
- Contradictory signals. Tehran claims to have closed the strait, while U.S. military command reports that more than 19 million barrels of oil passed through under convoy in a day.
High prices make voyages commercially viable even amid military risks: demand from Asian buyers encourages shipowners to continue transportation.
IEA and G7: Second Major Reserve Release This Year
The IEA has decided to release the remaining 100 million barrels into the market as part of the March agreement, including over 20 million barrels of diesel fuel. This follows the G7 agreement from October 2, which prioritized diesel delivery over four months.
- The diesel refining margin in Europe has decreased by nearly 2% following the announcement.
- Several analysts believe that the reserves only partially ease the tensions in the middle distillates market.
- The U.S. is considering easing sanctions on "shadow fleet" vessels to reduce record freight rates.
Heavy Fuel Oil—A New Narrow Segment
Besides diesel, the shortage of marine fuel is intensifying. According to Vitol, the conflict in the Middle East has reduced heavy fuel oil supplies from the Persian Gulf by approximately 800,000 barrels per month, while strikes on Russian refineries have cut another 1 million tons per month. For bunkering companies and shipping, this means sustained high fuel prices.
OPEC+: Quotas on Pause, Production Below Targets
Seven key OPEC+ members—Saudi Arabia, Russia, Iraq, Kuwait, Kazakhstan, Algeria, and Oman—have kept quotas for November unchanged.
- Target levels: around 10.5 million barrels per day for Saudi Arabia, 9.9 million for Russia, and 4.4 million for Iraq.
- Actual production from the core alliance in August averaged about 25 million barrels per day—about 5 million below pre-war levels.
- Approximately 2 million barrels per day of cuts remain in place.
- An audit of production capacities will determine the base production levels for 2027.
The next meeting of the alliance is scheduled for November 1. OPEC+'s influence on the physical oil market remains limited: logistics in the Persian Gulf play a decisive role.
Gas and LNG: Europe Enters Winter with Inventory Shortage
The European gas market remains one of the most strained segments of the global energy sector.
- Prices: TTF futures trade around €86 per MWh, which is approximately 2.6 times higher than last year's level.
- Storage: EU gas storage facilities are roughly 74% full, compared to a five-year average of about 89%. Brussels has lowered the target from 90% to 80%.
- Asia: The JKM indicator remains around $26 per MMBtu; Europe and Asia are competing for every LNG cargo.
During the Russian Energy Week, the notion of a "golden age" for gas was presented: it is no longer seen merely as a transition fuel. Notably, SOCAR announced its intention to purchase gas from Gazprom—a signal of a reconfiguration of regional gas flows.
Coal: Expensive LNG Restores Demand in Asia
Newcastle thermal coal trades around $150 per ton. The October high of $152.20 marks the highest level since October 2024, with a year-on-year increase exceeding 40%.
- High-quality thermal coal is approximately $20 per MMBtu cheaper than LNG in key Asian markets.
- The combined coal imports by China, Japan, and South Korea in Q4 may increase by approximately 20 million tons.
- In Russia, industry estimates suggest that losses for coal producers in 2027 could decrease by about 200 billion rubles.
Electric Power and Renewables: Focus on Reliability
The energy crisis is accelerating investments in both renewable energy and backup generation.
- In Europe, energy companies are combining solar power plants with storage solutions to reduce dependence on gas during peak hours.
- In Russia, Gazprom Energoholding plans new plants in Moscow with a capacity of up to 480 MW, while distributed generation is discussed as a necessary measure.
- On October 29, the IEA will present the Renewables 2026 report with updated forecasts for renewable capacity additions.
Russia: Oil Products Market, Refineries, and Production
The domestic fuel market in Russia is showing short-term stabilization amid restrictions and a diesel deal with the U.S.
- Retail: The average price of gasoline is 78.68 rubles per liter, and diesel fuel is 86.67 rubles. Since the beginning of the year, gasoline prices have risen by 21.4%, and diesel by 13.5%.
- Export: The ban on gasoline exports is in place until January 31, 2027, while restrictions on diesel exports have been lifted ahead of schedule.
- Diesel deal: Supplies to the U.S. and global market are 300,000 tons in October, 500,000 tons in November, and 1 million tons in December.
- Production: The Layaozhskoye field in the Arctic region has commenced pilot production. The Ministry of Energy and the Ministry of Finance are adjusting tax incentives for difficult-to-extract reserves.
A key risk for the refining sector is the status of refineries after the breakdown of the "energy truce": the volume of exported oil products is directly dependent on the operational capacity of the refineries.
What Matters for Energy Sector Investors Next Week
- Strait of Hormuz: Increasing oil flows may reduce the risk premium, while new attacks could push Brent back to $110.
- IEA reserves: The rate of diesel reaching the market will influence crack spreads and refinery margins.
- Sanctions against "shadow fleet": An official U.S. decision could reduce freight rates.
- EIA data on U.S. oil inventories on October 21.
- Bank of Russia meeting on October 23: inflation has accelerated to 7.2%, crucial for evaluating oil and gas company shares.
- Political calendar: OPEC+ meeting on November 1 and midterm elections in the U.S. on November 3.
The week in summary: the global markets for oil, gas, coal, and oil products remain structurally deficient. The release of strategic reserves and new logistical schemes temper price spikes, but do not eliminate the main cause of tension—the instability of supplies from the Persian Gulf. For participants in the energy sector, the priorities remain hedging price risks, diversifying supplies, and managing refining margins.